Reverse Mortgage Broker Serving San Francisco, California
The Sunset and the Richmond are full of owners who bought when a teacher’s salary could buy a house in San Francisco — and stayed fifty years. Their houses became fortunes; their incomes didn’t. That gap is exactly what this tool closes.
Sixteen of twenty-two capped: the city prices past the program.
FHA’s public endorsement file turns even a thin market like this one into something countable. San Francisco County, across the September 2025 through August 2026 monthly releases:
| HECMs insured by FHA, San Francisco County | 24 |
| Of those, purchases (HECM for Purchase) | 0 |
| Reached the FHA ceiling | 66.7% |
| In San Francisco itself | 22 |
| San Francisco: reached the ceiling | 16 of 22 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
San Francisco County’s endorsement record is the starkest on my map: 66.7% of the FHA loans insured here in the past year reached the federal ceiling. That is a description of recorded loans, not a rule about yours, but when two thirds of a county’s files hit the cap, the proprietary calculation has earned the right to go first.
The city’s own count, 22 insured loans with 16 capped, is small enough to treat as a tally rather than a trend, and it still points the same direction the values do.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
San Francisco by ZIP code
Twenty-six ZIP codes, eleven typing under the 2026 limit and fifteen over it, the Richmond to the Excelsior. The past year’s recorded loans and values:
San Francisco HECMs insured in the past year
Of the 26 San Francisco ZIP codes, 11 have a typical value under the $1,249,125 limit and 15 are over it; typical values run from about $742,000 to $2.6 million. The most loans were in 94112: 6 of the 22. Of the 22 loans, 16 reached the FHA ceiling, so the jumbo comparison matters here.
Show all 26 San Francisco ZIP codes
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 94102 | 0 | 0 | $742,000 | Under |
| 94103 | 1 | 1 | $827,000 | Under |
| 94104 | 0 | 0 | $1,149,000 | Under |
| 94105 | 0 | 0 | $1,131,000 | Under |
| 94107 | 0 | 0 | $1,055,000 | Under |
| 94108 | 1 | 1 | $1,049,000 | Under |
| 94109 | 0 | 0 | $1,072,000 | Under |
| 94110 | 1 | 1 | $1,446,000 | Over |
| 94111 | 0 | 0 | $1,143,000 | Under |
| 94112 | 6 | 4 | $1,183,000 | Under |
| 94114 | 0 | 0 | $2,049,000 | Over |
| 94115 | 0 | 0 | $1,576,000 | Over |
| 94116 | 2 | 2 | $1,647,000 | Over |
| 94117 | 0 | 0 | $1,703,000 | Over |
| 94118 | 0 | 0 | $2,309,000 | Over |
| 94121 | 0 | 0 | $1,863,000 | Over |
| 94122 | 2 | 2 | $1,740,000 | Over |
| 94123 | 1 | 1 | $2,553,000 | Over |
| 94124 | 3 | 0 | $938,000 | Under |
| 94127 | 3 | 3 | $2,056,000 | Over |
| 94129 | 0 | 0 | $1,785,000 | Over |
| 94131 | 1 | 1 | $1,785,000 | Over |
| 94132 | 1 | 0 | $1,403,000 | Over |
| 94133 | 0 | 0 | $1,409,000 | Over |
| 94134 | 0 | 0 | $1,094,000 | Under |
| 94158 | 0 | 0 | $1,381,000 | Over |
All 22 HECMs HUD recorded with a San Francisco address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 11 FHA-approved condominium projects with a San Francisco mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each San Francisco loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The San Francisco answer: jumbo first, usually. A typical value near $1,441,000, and rising sharply this year, outruns the 2026 HECM maximum claim amount of $1,249,125, so the federal program caps its calculation while proprietary programs work the actual value to $4 million from age 55. The HECM keeps a real role on the under-limit side of town and in the city’s specialty, owner-occupied 2-to-4-unit buildings, for owners 62 and older. Both routes carry no required monthly principal-and-interest payment while you live there with taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The San Francisco picture
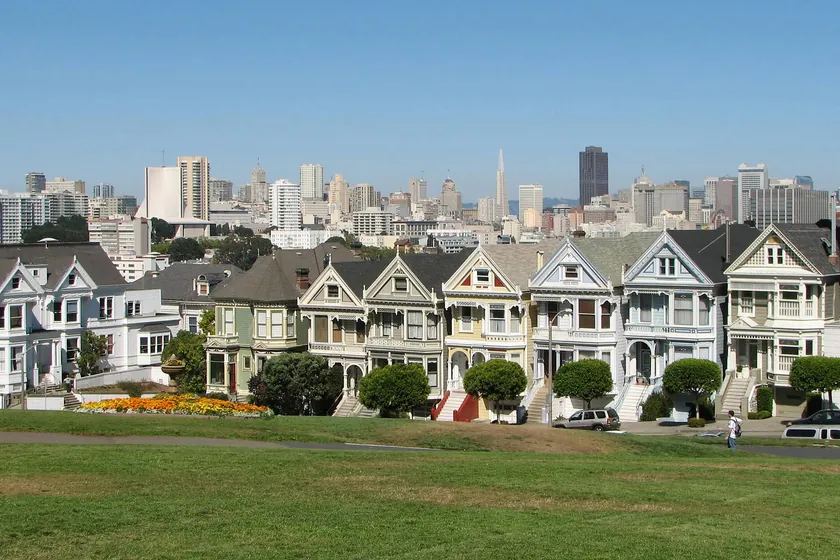
San Francisco holds the sharpest house-rich, income-modest divide in California. Zillow’s citywide average near $1,441,000, up strongly this year, sits above the 2026 FHA HECM limit of $1,249,125, so the typical single-family file here compares a limit-capped HECM against proprietary jumbo programs that lend on actual value to $4 million from age 55. In the Sunset, the Richmond, the Excelsior, and Bernal, where a rowhouse bought in 1978 now carries seven figures, that comparison decides real money.
Property type is destiny in this city, so let me be direct: tenancy-in-common (TIC) interests are not eligible for reverse mortgages: no FHA insurance, no mainstream proprietary program. Condominiums are eligible with FHA project or single-unit approval for a HECM, or under a jumbo lender’s own review. Single-family homes and, for HECMs, 2–4 unit buildings where you occupy a unit (a genuine San Francisco specialty) are routinely eligible. If you own a flat, the first question is what you legally own; I sort that before anything else.
The San Francisco client also arrives with the state’s deepest bench of professional advice (estate attorneys, fiduciary advisors, CPAs), and my practice is built for that table. The math goes to your advisor in writing; the trust goes to the lender’s counsel early; and if the answer is that selling under Prop 19 portability beats borrowing, you’ll hear that from me first.
The San Francisco files, sorted honestly
The Excelsior and Ingleside supplied six of the city’s 22 insured loans in the past year, more than any other ZIP code, on a typical value of about $1,183,000, under the limit. Long-held rowhouses, often the last affordable deeds from a different San Francisco, are where the federal program still counts the whole house and the growing credit line does its best work.
Owner-occupied 2-to-4-unit buildings are HECM-eligible when you live in one unit, and the appraisal values the entire building while the flats’ rent keeps arriving. A no-payment loan on an income property you also live in is a cash-flow structure most owners have never been shown. It is also the most San Francisco file there is, and I handle the tenant and lease questions that come with it.
Condo, co-op, TIC: three ways this city holds title, three different answers. Approved condos can take a HECM; co-ops cannot; TIC shares need their own conversation and usually a different tool. I read the vesting deed and the project status in the first twenty minutes, because quoting a program the building cannot legally take wastes everyone’s week.
How each program fits San Francisco
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical San Francisco home lands; your own age and value may point elsewhere.
What every San Francisco borrower must know
Who qualifies: proprietary jumbo from age 55, the FHA HECM from 62, on a primary residence with genuine equity and a financial assessment that carries the obligations below. In this city, property form matters as much as age: house, approved condo, and owner-occupied 2-to-4-unit buildings all have paths; co-ops do not. HECMs begin with counseling from a HUD-approved agency you pick off the federal roster (national line: 800-569-4287), with California’s cooling-off period behind it.
What stays yours to pay: San Francisco’s property tax bill with its bonds and assessments, insurance the appraisal district’s realities demand, HOA dues on condo files, and upkeep on housing stock that is often a century old. Current on those, no monthly mortgage payment is required while you live in the home; delinquent, the loan can be called due. On multi-unit files I also budget the building’s obligations honestly, because the rent only helps if the roof holds.
What protects you: title stays with you or your trust, flats and all. Non-recourse protection caps any repayment at the property’s value, and when the building eventually sells, every dollar beyond the balance belongs to you or your heirs.
Fifty-year tenures make San Francisco the Prop 13 capital of California: assessments from the Carter administration on homes worth $1.5 million. A reverse mortgage leaves the assessment untouched. Proposition 19 gives owners 55+ statewide portability of that base, up to three times, which is why ‘borrow and stay’ versus ‘sell, port the base, and right-size’ is the genuine strategic fork here, and I’ll model both sides of it with your advisor.
San Francisco questions, straight answers
I own a TIC share in a six-unit building. Can I get a reverse mortgage?
No: TIC interests aren’t eligible for HECM or mainstream jumbo reverse programs. If the building later converts to condominiums, eligibility opens up (with FHA or lender approval of the project). I’d rather tell you this in one minute than let anyone string you along for six weeks.
We own our two-flat and live upstairs. Does the rental unit disqualify us?
The opposite: it’s a classic San Francisco HECM. FHA allows 2–4 unit properties when one unit is your primary residence. The downstairs rent keeps arriving; your mortgage payment, if any, goes away at closing. Tenant and rent-ordinance questions stay exactly as they are; the loan doesn’t change your obligations as a landlord.
Our house in the Sunset is worth $1.6M. HECM or jumbo?
At $1.6M the HECM computes proceeds as if the home were worth $1,249,125; the jumbo computes on $1.6M with no FHA premium and, if relevant, eligibility at 55. The jumbo usually generates more; the HECM answers with its growing credit line. Both go on one page for you and your advisor.
Is it smarter to just sell and leave the city?
Sometimes yes, and under Prop 19 you’d carry your low tax base anywhere in California. That’s a life decision wearing a financial costume. My job is to price the ‘stay’ option accurately so you’re choosing between real numbers, not guesses; several clients a year hear me say selling wins.
Our Sunset house has a legalized in-law unit downstairs. Does that change the program?
Usually it stays a single-family file with an accessory unit, valued accordingly, and legalization helps you: permitted space appraises, unpermitted space gets discounted or conditioned. If the property is legally a 2-unit, the 2-to-4-unit HECM rules apply instead, which is often better. Bring the permit history and I will tell you which file you actually have.
Prop 13 keeps our taxes tiny, but our insurance quote tripled. Does the file still work?
Often yes, precisely because the tax side is so light. The assessment weighs the whole stack, taxes, insurance, dues, against income and assets, and SF files usually pass on the strength of equity and low taxes even with a hard insurance market. Where it is tight, a set-aside funds the premiums from proceeds and settles the question.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
San Francisco’s follow-up questions, each on its own page:
- What a reverse mortgage actually costs: both programs’ costs in dollars, at San Francisco scale.
- HECM line of credit compared with a bank HELOC: the credit-line question for equity-heavy, income-light years.
- The reverse mortgage glossary: the vocabulary, from maximum claim amount to set-aside.
- Who qualifies for a reverse mortgage: the six requirements, with the 2-to-4-unit and condo rules.
- How reverse mortgage rates work: how jumbo pricing and the HECM margin really compare.
- Helping a parent decide: for the kids in the East Bay or back east, before Mom decides.
Since most of this city prices past the federal line, jumbo reverse mortgages for California homes is required reading here.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your San Francisco numbers.
One call sorts your San Francisco file: which programs your title can take, and what each one produces, in writing.
- A call back within minutes during California business hours
- Title and project eligibility read before anything is promised
- A plain no when the building or the math says no
Rather talk it through now?
Tell me what you own, house, flats, condo, or TIC share, and the neighborhood, and I will tell you which doors are open before we talk numbers. In San Francisco the paperwork picks the program; the records above just confirm how often that program turns out to be the jumbo.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide