Home Equity Solutions for the Family Law Practice
The settlement that closes is the one somebody underwrote first. The agreement says one spouse will refinance and buy out the other within twelve months, and nobody verified whether that spouse can qualify on a single retirement income. This is the reference for the housing side of a gray divorce file: what the loan can fund, and what the judgment has to say for it to fund at all.
Thirty-seven pages, sixteen case files, with the numbers run at published rates and the authorities cited inline (24 C.F.R. §206.25, Fam. Code §§760, 2581, 2640, 2040, Moore/Marsden, Watts/Epstein, IRC §§1041 and 121). Read Files 1 and 2 first — between them they decide whether a reverse mortgage can fund a buyout at all, and both turn on drafting.
Three things that decide a file, none of which are on the lender’s side of the desk
A large share of gray divorce files founder on the house, because the only financing anyone in the room knows about is a conventional refinance that a single retirement income cannot carry. There is a second tool. Whether it works turns almost entirely on how you draft.
How the equalization is written
Federal rule caps first-year disbursements at the greater of 60% of the principal limit or mandatory obligations plus 10% (24 C.F.R. §206.25). Mandatory obligations include amounts required to discharge existing liens on the property. An equalization secured by a recorded lien funds as a lien payoff; a bare obligation comes out of the 60%. Same house, same borrower, very different day-one number.
When the loan closes
Close while the parties are still married and the departing spouse becomes a non-borrowing spouse: the principal limit is computed on the younger of the two ages, and the ex signs the loan papers. Judgment, then the interspousal transfer deed, then funding — and the automatic restraining orders bar encumbering the residence before that without a stipulation.
What the loan actually lends
Roughly a third of value in the sixties at today’s rates, against an equal division that asks for half. File 1 states the gap plainly and the remaining files are about how the facts of a real case — a separate-property interest, a §2640 reimbursement, an asset trade — move the number.
Sixteen case files, ordered for your practice
Each file states the mechanics, the governing rule, the trap, and a composite fact pattern with the numbers run.
Start here
- File 1 · The paid-off house and the honest gap
- File 2 · Writing the equalization as a recorded lien
- File 9 · Closing before the judgment: the non-borrowing-spouse trap
- File 3 · The asset trade: the house against the accounts
- File 6 · Sell, and both spouses purchase
- File 14 · The support-dependent spouse and the financial assessment
The rest
- The house that still has a mortgage · the departing spouse and HECM for Purchase
- The under-62 spouse, the low-rate first, and the private 55+ programs
- The couple who already have a reverse mortgage
- Moore/Marsden · §2640 · Watts and Epstein · deferred sale orders
- The ten-year Social Security cliff and the rest of the calendar
- The tax file: §1041, §121 and what the retaining spouse inherits
No compensation changes hands. Ever.
RESPA §8 prohibits giving or receiving anything of value for referrals on these loans (12 U.S.C. §2607). You will never be offered a dollar by me, which is precisely what keeps your independence, and your State Bar file, outside the transaction. Education like this book is expressly permitted (12 C.F.R. §1024.14(g)(1)); payments are not, in either direction.
Your exposure, itemized
Compensation to you: none, prohibited and never offered. Your regulatory involvement: none — you remain purely advisory and the loan is client-to-lender. Cross-sell risk to your client: none. Your client relationship: untouched, and documented as such on every file.
An honest no, in writing
Roughly a third of the files that cross my desk end with me saying the loan is wrong, in writing, copied to you. In a buyout file that usually means the house should be sold — far better said before the settlement than after.
Written analysis in five business days
Both sides of the file where both apply: what the retaining spouse’s loan can fund as a recorded lien and as an unsecured obligation, what the departing spouse could buy, and the sell-and-both-purchase alternative. Drafted to attach to a settlement conference statement.
Where should Ken send it?
No pitch, no ask, and no follow-up campaign.
Prefer to skip the form? Call (818) 674-7284 or email ken@ideal-financial.net and ask for the family law guide.
Estate planning, trust or probate? The estate planning edition. Elder law? The elder law edition. A client who needs the plain-English version? Send them the free consumer guide or the buyout calculator, which needs no contact details.
Where should Ken send it?
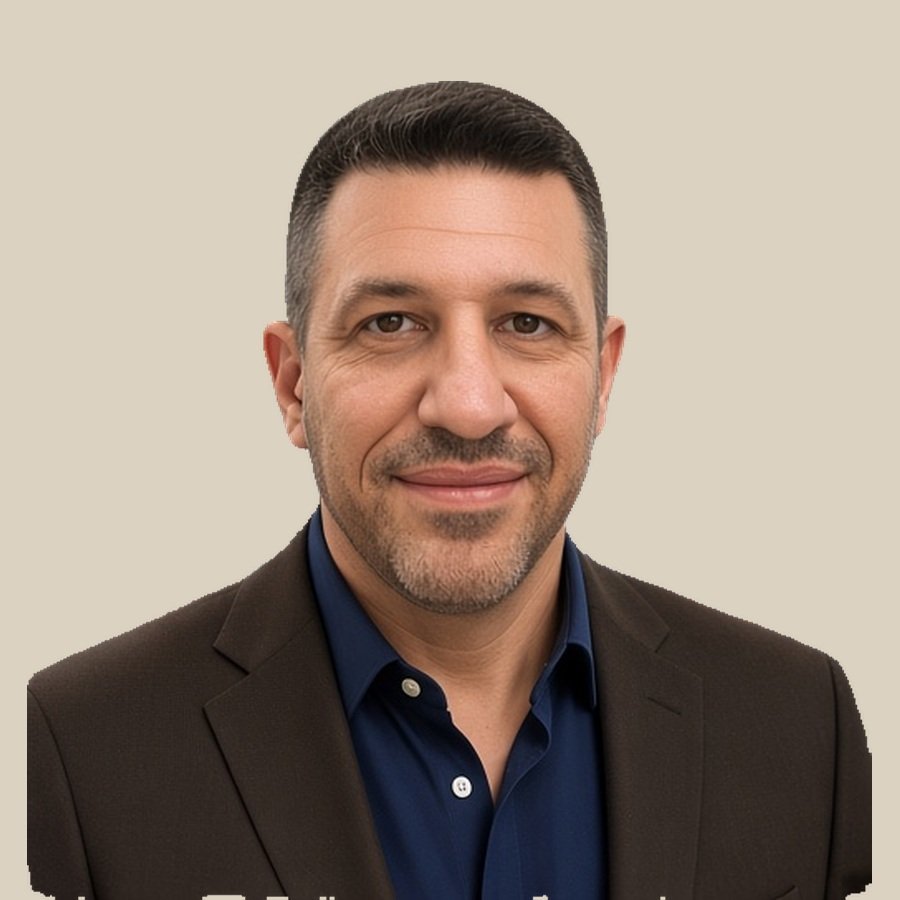
Written by Kenneth M. Adler
Broker & Owner, Ideal Financial, Inc. · 30 years in California lending · NMLS #240317 · CA DRE #01216608
Published September 20, 2026 · Last reviewed September 20, 2026
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The rest of the reverse mortgage library
Each page below covers one decision in full, rather than a paragraph of it. Start wherever your question is.
Fifteen minutes. Real numbers. Then you decide.
Tell me the scenario and I’ll tell you honestly whether this is the right tool. If it isn’t, you’ll leave the call knowing why, and I’ll point you at whatever is.
(818) 674-7284Prefer email?
Send a couple of sentences about your situation and I’ll reply personally, usually the same business day.
Contact Ken Book a 30-minute call