Reverse Mortgage Broker Serving San Jose, California
Willow Glen, Cambrian, Almaden: the modest ranch homes of orchard-era San Jose became some of the most valuable ordinary houses on earth. The owners who never sold are sitting on the retirement plan they never had to fund.
Forty-eight of sixty-nine capped: the valley writes jumbo files.
Every FHA reverse mortgage lands in HUD’s loan-level public file at endorsement. Here are Santa Clara County and San Jose across the twelve releases, September 2025 through August 2026.
| HECMs insured by FHA, Santa Clara County | 146 |
| Of those, purchases (HECM for Purchase) | 1 |
| Reached the FHA ceiling | 76.0% |
| In San Jose itself | 69 |
| San Jose: reached the ceiling | 69.6% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Santa Clara County’s past-year numbers leave little to argue about: 76.0% of insured reverse mortgages reached the FHA ceiling. Endorsement history, not a measurement of what every homeowner needs, but with three in four recorded loans capped, the proprietary quote opens the conversation here.
San Jose itself recorded 69 insured loans, 69.6% of them at the ceiling, the county pattern in city form. The federal limit is simply smaller than most of this valley’s houses.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
San Jose by ZIP code
One citywide number hides a city where typical values run from about $628,000 to about $2.5 million. Here is the same federal loan record, broken down by ZIP code, beside Zillow’s typical home value for each one.
San Jose HECMs insured in the past year
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 95124 | 8 | 8 | $1,860,000 | Over |
| 95127 | 8 | 2 | $1,066,000 | Under |
| 95123 | 6 | 6 | $1,301,000 | Over |
| 95125 | 6 | 6 | $1,818,000 | Over |
| 95132 | 5 | 5 | $1,537,000 | Over |
| 95135 | 5 | 2 | $1,679,000 | Over |
| 95136 | 5 | 4 | $1,301,000 | Over |
The 7 ZIP codes with five or more loans: 43 of the 69 HECMs HUD recorded with a San Jose address. The other 26 were spread across 13 more ZIP codes. The limit is the 2026 HECM maximum claim amount of $1,249,125.
In San Jose the ceiling is the rule: 48 of the 69 loans reached it, and in 95124, 95123, 95125 and 95132, all 25 did. Where typical values are lower, more loans fit under the limit: in 95127 (about $1,066,000) and 95122 (about $945,000), 9 of 11 stayed under it. For most San Jose homes, though, the HECM calculation stops at $1,249,125, which is why the jumbo comparison belongs in the first conversation.
Find your ZIP code: all 29 San Jose ZIP codes against the HECM limit
12 of the 29 ZIP codes Zillow assigns to the City of San Jose have a typical value under the $1,249,125 limit; 17 are above it.
- 95002$1,163,000Under
- 95110$797,000Under
- 95111$1,020,000Under
- 95112$956,000Under
- 95113$628,000Under
- 95116$897,000Under
- 95117$1,662,000Over
- 95118$1,572,000Over
- 95119$1,349,000Over
- 95120$2,153,000Over
- 95121$1,195,000Under
- 95122$945,000Under
- 95123$1,301,000Over
- 95124$1,860,000Over
- 95125$1,818,000Over
- 95126$1,148,000Under
- 95127$1,066,000Under
- 95128$1,401,000Over
- 95129$2,508,000Over
- 95130$2,022,000Over
- 95131$1,283,000Over
- 95132$1,537,000Over
- 95133$1,094,000Under
- 95134$1,009,000Under
- 95135$1,679,000Over
- 95136$1,301,000Over
- 95138$1,730,000Over
- 95139$1,284,000Over
- 95148$1,461,000Over
All 146 HECMs in Santa Clara County carried an adjustable rate, including all 69 with a San Jose address. Nationally it was 24,517 of 24,529. The reason is structural: a fixed-rate HECM is one lump sum at closing, limited by HUD’s first-year rules, with no line of credit afterward. Anyone who wants a line of credit or monthly payments takes the adjustable version.
For the typical San Jose borrower, the principal limit (the most the loan makes available) was 46.7% of the value HUD counted: the appraised value, or the FHA limit when the home is worth more. Countywide it was 48.2%. Age decides most of the difference from one borrower to the next: the older the youngest borrower, the higher the share.
HUD’s list shows 20 FHA-approved condominium projects with a San Jose mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each San Jose loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The San Jose answer: Silicon Valley arithmetic puts the proprietary jumbo first: typical values near $1.4 million exceed the 2026 HECM maximum claim amount of $1,249,125, so the federal calculation caps while jumbo programs recognize actual value to $4 million from age 55, and the record agrees, 48 of the city’s 69 insured loans in the past year were capped. East side and downtown-adjacent ZIP codes keep the HECM fully in play for owners 62 and older. Both programs require no monthly principal-and-interest payment while you live in the home with taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The San Jose picture
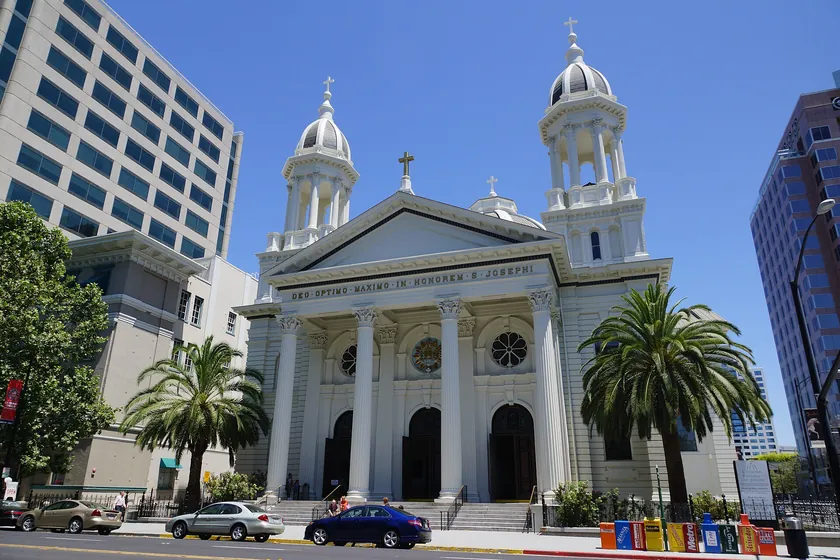
San Jose’s arithmetic is Silicon Valley’s doing: citywide values average roughly $1.4 million, comfortably above the 2026 FHA HECM limit of $1,249,125. A 1,600-square-foot Cambrian ranch bought in 1974 for $42,000 now supports a jumbo reverse mortgage computed on its actual value (up to $4 million, from age 55, no FHA premium) while the HECM runs alongside as the comparison, capped at the limit but armed with its growing credit line.
The valley’s signature client is the pre-tech retiree in a post-tech market: the teacher, the county employee, the machinist from the old plants, whose neighborhood appreciated around them while their pension stood still. The insult of being unable to afford the property taxes on a home you’ve owned fifty years is real here, and Prop 13 blunts most of it, but insurance, upkeep, and life itself still outrun a fixed income. Converting a slice of the valley’s appreciation into a credit line that requires no monthly principal and interest payment is the cleanest correction I know.
The other San Jose file is generational: parents with $1.5 million in equity and children priced out of the very market that created it. Structured with the family’s advisor, reverse mortgage proceeds fund down-payment gifts while the parents keep the home, the tax base, and the neighborhood: a transfer of opportunity that doesn’t wait for an inheritance.
San Jose’s records, street level
In 95124, 95123, 95125, and 95132, Cambrian, Blossom Valley, Willow Glen, Berryessa, every single insured loan in the past year reached the cap: 25 for 25. When a 1961 ranch holds $1.8 million of value, the federal program can only see $1,249,125 of it, and the question becomes what the other half-million should be doing. That is the jumbo conversation, and on these streets it is unavoidable.
95127 and 95122, Alum Rock to the eastern foothills’ feet, ran 9 of 11 loans under the limit on typical values of about $1,066,000 and $945,000. For those owners the HECM still counts essentially the whole house and brings its growing credit line, the feature no proprietary program matches. Two cities, one ZIP map; I quote accordingly.
Santa Clara County recorded exactly one HECM for Purchase in the past year. At valley prices the required 55-to-70-percent down payment is a large check, which is why the tool gets overlooked, yet for a downsizer leaving a $2 million Cambrian house for a $1.1 million single-level, it pencils beautifully: pay part, finance the rest with no required monthly principal-and-interest payment, and keep the difference liquid. Underused is not the same as unusable.
How each program fits San Jose
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical San Jose home lands; your own age and value may point elsewhere.
What every San Jose borrower must know
Who qualifies: proprietary jumbo from age 55, which fits how early this valley retires; the FHA HECM from 62. Primary residence status, real equity, and a financial assessment that supports the obligations below apply to both. The HECM route starts with counseling from a HUD-approved agency you choose from the federal roster (national line: 800-569-4287), and California’s cooling-off period follows signing.
Your continuing side of the deal: Santa Clara County’s tax bill in full, homeowner’s insurance, HOA dues where they apply, and upkeep on housing stock that mostly predates 1980. Keep those current and no monthly mortgage payment is required while you live in the home; fall behind and the loan can be called due. Set-asides that automate taxes and insurance remain the simple fix when a fixed income meets valley carrying costs.
What protects you: title remains in your name or your trust. Non-recourse protection means repayment can never exceed the home’s value, however the market moves, and all remaining equity at sale belongs to you or your heirs.
Orchard-era owners hold Prop 13 assessments that look like typographical errors next to today’s values, and a reverse mortgage preserves them untouched. Proposition 19 portability (55+, statewide, three transfers) frames the valley’s strategic question: fund the stay, or port the base and take the equity somewhere it stretches further. I model both; the family decides.
San Jose questions, straight answers
Our Almaden home appraises around $1.9M. What does jumbo actually get us?
Proceeds computed on $1.9M rather than the HECM’s $1,249,125 cap; at typical ages the difference is substantial. No FHA premium on the way in, non-recourse on the way out, and eligibility from 55. Exact figures depend on age and rates; I’ll run your address in minutes.
Can we use proceeds to help our kids buy in this market?
Yes: proceeds are yours, and down-payment gifts are among the most common uses I see in Santa Clara County. The receiving lender will document the gift normally. Structure it with your advisor and estate attorney; done well, it’s an inheritance delivered when it’s actually useful.
The market has softened this year. Should we wait?
Softening cuts both ways: proceeds are computed on appraised value, so a lower value means somewhat less, but a HECM credit line, once established, grows regardless of what the house does afterward, which is precisely why the research favors opening the line before you need it rather than timing the top.
Do you handle Eichlers and other atypical valley homes?
Yes: they appraise on comparables like everything else, and the valley has enough of them that comparables exist. Foam roofs and radiant systems draw appraiser commentary, not disqualification. Condition items, if flagged, are handled with set-asides as anywhere.
Our Cambrian ranch has decades of weekend remodeling. Do permit gaps hurt us?
They can, in the appraisal: unpermitted additions get valued cautiously or flagged for correction, and at San Jose prices that swing is real money. Sometimes the cure is retroactive permitting; sometimes we simply let the appraiser value the legal footprint. Tell me the house’s honest history up front and the strategy gets chosen before the appraisal, not after it.
Prop 19 already changed what our kids keep. Does a reverse mortgage make inheritance worse?
It does not change the tax rules at all: the loan is a lien, not a transfer, and your assessment stays yours while you live there. At your passing the balance is repaid from the home like any mortgage, heirs keep the remaining equity, and the Prop 19 reassessment questions play out exactly as they would have anyway. For the estate-planning fine points I will happily work alongside your attorney.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
What San Jose owners read next, each on its own page:
- What a reverse mortgage actually costs: all the costs in dollars, where valley stakes make them matter.
- HECM line of credit compared with a bank HELOC: the line that grows against the line a bank can trim mid-plan.
- The reverse mortgage glossary: every disclosure term, maximum claim amount first.
- Who qualifies for a reverse mortgage: the six requirements and the 55-to-61 proprietary door.
- How reverse mortgage rates work: what moves proceeds in each program, index to margin.
- Helping a parent decide: for adult children weighing the family house and the loan.
With most of the valley priced past the federal line, jumbo reverse mortgages for California homes is the natural next page.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your San Jose numbers.
One call and the San Jose comparison is in writing: actual-value jumbo beside the capped HECM, east side or west.
- A call back within minutes during California business hours
- Your ZIP code’s record quoted, not the citywide average
- When waiting or doing nothing wins, that is the advice
Rather talk it through now?
Give me the neighborhood and the ages and I will tell you which column your street has been choosing, then price both anyway. In a county where 76% of the recorded loans hit the federal cap, guessing is the one approach that costs money.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide