Reverse Mortgage Broker Serving Torrance, California
Torrance was built by people who built airplanes — and the tract homes their paychecks bought in the 60s and 70s are now seven-figure assets. That equity can now return the favor and fund the retirement.
Run both calculations here. Neither one is obvious.
Every FHA-insured reverse mortgage in the country is recorded by HUD, loan by loan. Here is what those records say about this market over the last twelve monthly releases (September 2025 through August 2026).
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Torrance itself | 22 |
| Torrance: reached the ceiling | 13 of 22 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
About 21% of federally insured reverse mortgages in this county hit the FHA ceiling, which means roughly 79% did not. That split is exactly why I run the HECM and the jumbo side by side rather than leading with one.
In Torrance itself, 22 of those loans were on homes inside the city limits and 13 of them reached the ceiling. That is too few loans for a percentage to mean much, so the county rate is the one to plan around; the raw count is here because it is a fact, not a trend.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Torrance by ZIP code
Torrance is small enough to show whole: five ZIP codes, with typical values from about $726,000 to $1.41 million, on both sides of the HECM limit. Here is the same federal loan record, ZIP code by ZIP code, beside Zillow’s typical home value for each one.
Torrance HECMs insured in the past year
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 90501 | 6 | 3 | $972,000 | Under |
| 90502 | 1 | 0 | $726,000 | Under |
| 90503 | 4 | 3 | $1,275,000 | Over |
| 90504 | 4 | 1 | $986,000 | Under |
| 90505 | 6 | 5 | $1,410,000 | Over |
All 22 HECMs HUD recorded with a Torrance address; one of them carried ZIP code 90277, which Zillow files under Redondo Beach, and is not in the table. The limit is the 2026 HECM maximum claim amount of $1,249,125.
The split follows the map. In 90503 and 90505, on the city’s west and south sides, typical values are over the limit and 8 of 10 loans reached the ceiling. In 90501, 90502 and 90504 the typical home is under the limit, though 4 of 11 loans there still reached it: a typical value is the middle of the market, not every house.
Of the 818 HECMs in Los Angeles County, 817 carried an adjustable rate, and all 22 with a Torrance address did. Nationally it was 24,517 of 24,529. The reason is structural: a fixed-rate HECM is one lump sum at closing, limited by HUD’s first-year rules, with no line of credit afterward. Anyone who wants a line of credit or monthly payments takes the adjustable version.
Across Los Angeles County, the typical borrower’s principal limit (the most the loan makes available) was 45.4% of the value HUD counted: the appraised value, or the FHA limit when the home is worth more. Torrance’s 22 loans are too few for a percentage of their own. Age decides most of the difference from one borrower to the next: the older the youngest borrower, the higher the share.
HUD’s list shows 11 FHA-approved condominium projects with a Torrance mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the same HUD HECM Snapshot records as above, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Torrance loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The short answer for Torrance: for homeowners 62 and older, the FHA-insured HECM fits most Torrance homes. The typical value here (about $1,100,000) sits under the 2026 HECM maximum claim amount of $1,249,125, so the calculation reaches essentially the full value. Homes above the limit, and owners aged 55 to 61, are served by proprietary jumbo programs on values to $4 million. Either way, no monthly principal-and-interest payment is required while you live in the home and keep property taxes, insurance, and maintenance current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Torrance picture
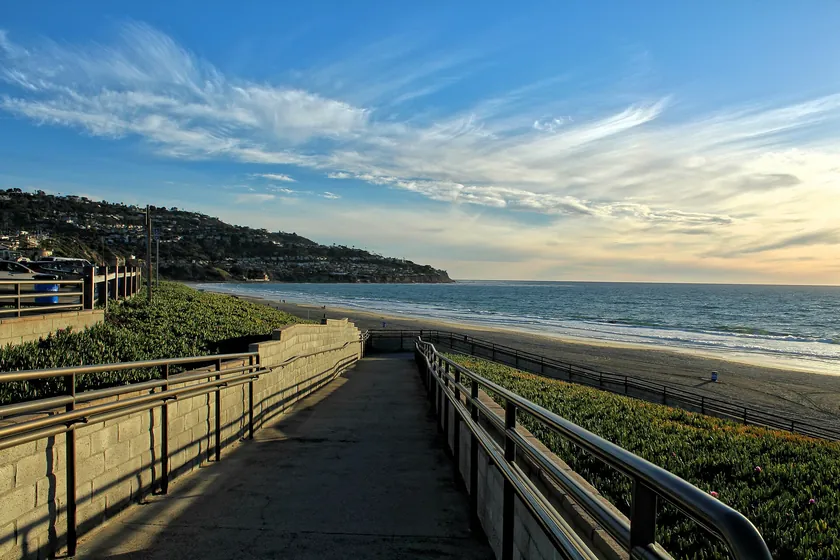
The South Bay’s aerospace generation is the heart of my Torrance work. Careers at the airframe and defense plants that once ringed this city bought homes in Walteria, Seaside, Southwood, and the Hollywood Riviera, and those homes now average about $1,100,000 citywide, just under the 2026 FHA HECM limit of $1,249,125. That positioning is genuinely favorable: the HECM calculation reaches essentially the full value of a typical Torrance home, while Riviera view properties above the limit are served by jumbo programs to $4 million.
Torrance is also one of Southern California’s best cities to age in place, and my clients here say so explicitly: two major hospitals in town, flat walkable tracts, the ocean air. The most common structure I write here is the standby line of credit (no required draw, growing over time) positioned as the funding source for future in-home care so that staying in the house remains affordable for the long haul.
A pattern worth naming: many Torrance retirees carry excellent pensions but modest liquid savings, because the house absorbed the wealth. A reverse mortgage rebalances that, converting a slice of home equity into liquidity or eliminating a lingering mortgage payment: without selling the home, with no required monthly principal and interest payment, and without touching the Prop 13 tax base.
How each program fits Torrance
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Torrance home lands; your own age and value may point elsewhere.
What every Torrance borrower must know
Who qualifies: homeowners 62+ for the FHA HECM (55+ for many jumbo programs), living in the home as their primary residence, with sufficient equity and a financial assessment showing capacity to meet the obligations below. Independent counseling with a HUD-approved agency is required before a HECM, and you choose the agency freely from the HUD roster (national line: 800-569-4287), and California adds its own consumer protections, including a cooling-off period.
What you must keep paying: property taxes (every line of the bill), homeowner’s insurance, reasonable home maintenance, and HOA dues where applicable. No monthly mortgage payment is required while you live in the home and meet these obligations, but failing to meet them can cause the loan to become due and payable. I structure set-asides when automating these payments is the safer plan.
What protects you: title stays in your name or your trust; the loan is non-recourse, so neither you nor your heirs can owe more than the home’s value; and heirs keep every dollar of remaining equity when the home is sold.
South Bay owners who bought in the 1960s–80s often pay property taxes on a small fraction of today’s value thanks to Proposition 13. A reverse mortgage leaves that assessment exactly where it is. If the long-range plan is to right-size (common here as the big tract two-story becomes too much house), Proposition 19 lets owners 55+ carry the low tax base to the replacement home, and a HECM for Purchase can finance that move without creating a new monthly payment.
Torrance questions, straight answers
What does a reverse mortgage cost, honestly?
Upfront: origination, standard closing costs, and on the HECM an FHA initial mortgage insurance premium of 2% of the maximum claim amount, most of it financeable into the loan. Ongoing: interest and, on HECMs, an annual 0.5% insurance accrual. Jumbo programs carry no FHA premium. I put every number on one page before you decide; if the math doesn’t serve you, I’ll say so.
Can I use the line of credit for future in-home care?
Yes: that is precisely what the standby structure is for. The unused HECM line grows over time regardless of your home’s value, so a line opened at 68 can be a substantially larger care-funding resource at 80. It’s the most common plan I build for Torrance clients who intend to stay.
My spouse is 58 and I’m 63. Can we do this?
Yes, two ways: a jumbo program can include your spouse as a full co-borrower from age 55, or a HECM can be structured with your spouse as an eligible non-borrowing spouse who is protected in the home. Proceeds are based on the younger age either way. I’ll show you both structures side by side.
We own a two-story and want single-level. How does HECM for Purchase work?
You sell, then buy the single-level home using roughly 55 to 70 percent of the price in cash from your sale proceeds (it depends on your age, and closing costs are extra) while the HECM finances the balance, with no required monthly principal-and-interest payment. Compared with paying all cash, it leaves several hundred thousand dollars liquid in your accounts instead of stranded in the new house.
Written by Kenneth M. Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
These questions come up on nearly every Torrance file, and each one has a page of its own rather than a paragraph buried somewhere:
- What a reverse mortgage actually costs — the six cost categories, which of them get financed rather than paid at the table, and why “no cost” advertising is misleading.
- HECM line of credit compared with a bank HELOC — required payments, whether the lender can freeze the line, and the cases where the HELOC is genuinely the better tool for a Torrance homeowner.
- The reverse mortgage glossary — forty-eight terms defined plainly, for anyone reading a disclosure and wondering what a principal limit factor or a LESA actually is.
- Who qualifies for a reverse mortgage — the six requirements on one page, and the jumbo route from age 55.
- How reverse mortgage rates work — index, margin and the expected rate, and how to compare two quotes.
- Helping a parent decide — what adult children should know about the house, the inheritance and the questions to ask.
If your Torrance home is worth more than the FHA calculation will count, start instead with jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Torrance numbers.
Fifteen minutes on the phone and you’ll know what your home and your age actually produce, HECM and jumbo side by side.
- A call back within minutes during California business hours
- Your figures in writing before you commit to anything
- If it is the wrong tool for you, I will say so
Rather talk it through now?
Tell me the scenario and I’ll tell you honestly whether this is the right tool. If it isn’t, you’ll leave the call knowing why, and I’ll point you at whatever is.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide