Reverse Mortgage Broker Serving Los Angeles, California
From the Valley to the Westside, Los Angeles homeowners hold more housing wealth than almost anyone in America, and most of it is locked inside the house. I’ve spent 30 years helping Californians put it to work with no required monthly mortgage payment, as long as they keep up the taxes, insurance and upkeep.
A ninety-five ZIP city needs both columns priced.
HUD publishes every FHA-insured reverse mortgage it endorses, address by address. Below is what the twelve monthly releases from September 2025 through August 2026 show for Los Angeles County and for the city itself.
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Los Angeles itself | 177 |
| Los Angeles: reached the ceiling | 26.0% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Across Los Angeles County, 21% of the FHA loans endorsed in the past year reached the ceiling and 79% did not. Treat that as endorsement history rather than a verdict on your house: it is the reason I price the HECM and the jumbo together on the first call instead of assuming either.
The city itself accounts for 177 of those insured loans, and 26.0% of them reached the ceiling, a higher share than the county as a whole. Whether yours would is a question your ZIP code answers better than the citywide average does.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Los Angeles by ZIP code
One citywide number hides a city where typical values run from about $516,000 to more than $3 million. Here is the same federal loan record, broken down by ZIP code, beside Zillow’s typical home value for each one.
Los Angeles HECMs insured in the past year
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 90047 | 16 | 0 | $688,000 | Under |
| 90043 | 12 | 1 | $809,000 | Under |
| 90044 | 10 | 0 | $642,000 | Under |
| 90008 | 8 | 2 | $1,034,000 | Under |
| 90039 | 8 | 4 | $1,333,000 | Over |
| 90018 | 7 | 2 | $822,000 | Under |
| 90059 | 6 | 0 | $613,000 | Under |
| 91304 | 6 | 1 | $913,000 | Under |
| 90019 | 5 | 3 | $1,170,000 | Under |
| 90061 | 5 | 0 | $631,000 | Under |
| 90068 | 5 | 4 | $1,620,000 | Over |
The 11 ZIP codes with five or more loans: 88 of the 177 HECMs HUD recorded with a Los Angeles address. The other 89 were spread across 46 more ZIP codes. The limit is the 2026 HECM maximum claim amount of $1,249,125.
The busiest ZIP codes are not the expensive ones. In 90047, 90043 and 90044, where typical values run from about $642,000 to $809,000, 38 loans were insured and only one reached the ceiling: owners of moderately priced homes, exactly who the FHA program was built for. In 90039 and 90068, where values run past $1.3 million, more than half of the loans reached the ceiling (8 of 13). That is where the jumbo comparison earns its keep.
Find your ZIP code: all 95 Los Angeles ZIP codes against the HECM limit
69 of the 95 ZIP codes Zillow assigns to the City of Los Angeles have a typical value under the $1,249,125 limit; 26 are above it.
- 90002$592,000Under
- 90003$601,000Under
- 90004$1,381,000Over
- 90005$866,000Under
- 90006$721,000Under
- 90007$869,000Under
- 90008$1,034,000Under
- 90010$933,000Under
- 90011$600,000Under
- 90012$579,000Under
- 90013$534,000Under
- 90014$516,000Under
- 90015$605,000Under
- 90016$900,000Under
- 90017$578,000Under
- 90018$822,000Under
- 90019$1,170,000Under
- 90020$667,000Under
- 90021$836,000Under
- 90023$635,000Under
- 90024$1,334,000Over
- 90025$1,051,000Under
- 90026$1,141,000Under
- 90027$1,769,000Over
- 90028$860,000Under
- 90029$953,000Under
- 90031$792,000Under
- 90032$786,000Under
- 90033$645,000Under
- 90034$1,406,000Over
- 90035$1,593,000Over
- 90036$1,808,000Over
- 90037$660,000Under
- 90038$994,000Under
- 90039$1,333,000Over
- 90041$1,268,000Over
- 90042$964,000Under
- 90043$809,000Under
- 90044$642,000Under
- 90045$1,470,000Over
- 90046$1,432,000Over
- 90047$688,000Under
- 90048$1,749,000Over
- 90049$2,967,000Over
- 90057$536,000Under
- 90062$684,000Under
- 90064$1,834,000Over
- 90065$1,086,000Under
- 90066$1,693,000Over
- 90067$1,580,000Over
- 90068$1,620,000Over
- 90077$3,062,000Over
- 90094$1,332,000Over
- 90248$800,000Under
- 90272$2,850,000Over
- 90291$1,907,000Over
- 90293$891,000Under
- 90710$827,000Under
- 90731$822,000Under
- 90732$875,000Under
- 90744$679,000Under
- 91040$906,000Under
- 91042$878,000Under
- 91303$729,000Under
- 91304$913,000Under
- 91306$815,000Under
- 91311$927,000Under
- 91316$943,000Under
- 91324$922,000Under
- 91325$1,019,000Under
- 91326$1,207,000Under
- 91331$727,000Under
- 91335$786,000Under
- 91342$788,000Under
- 91343$864,000Under
- 91344$976,000Under
- 91345$812,000Under
- 91352$797,000Under
- 91356$1,326,000Over
- 91364$1,273,000Over
- 91367$1,090,000Under
- 91401$1,077,000Under
- 91402$693,000Under
- 91403$1,430,000Over
- 91405$814,000Under
- 91406$837,000Under
- 91411$956,000Under
- 91423$1,403,000Over
- 91436$2,181,000Over
- 91601$885,000Under
- 91602$1,038,000Under
- 91604$1,660,000Over
- 91605$840,000Under
- 91606$849,000Under
- 91607$1,222,000Under
Of the 818 HECMs in Los Angeles County, 817 carried an adjustable rate, and all 177 with a Los Angeles address did. Nationally it was 24,517 of 24,529. The reason is structural: a fixed-rate HECM is one lump sum at closing, limited by HUD’s first-year rules, with no line of credit afterward. Anyone who wants a line of credit or monthly payments takes the adjustable version.
For the typical Los Angeles borrower, the principal limit (the most the loan makes available) was 46.5% of the value HUD counted: the appraised value, or the FHA limit when the home is worth more. Countywide it was 45.4%. Age decides most of the difference from one borrower to the next: the older the youngest borrower, the higher the share.
HUD’s list shows 19 FHA-approved condominium projects with a Los Angeles mailing address (searched October 16, 2026). If your address uses a neighborhood name, such as Sherman Oaks or Encino, search under that name. A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the same HUD HECM Snapshot records as above, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Los Angeles loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Los Angeles bottom line: at a citywide typical value near $928,000, most homes sit under the 2026 HECM maximum claim amount of $1,249,125, so the federally insured program calculates against essentially everything the house is worth for owners 62 and older. The hillside and Westside exceptions, and owners aged 55 to 61, move to proprietary jumbo programs on values to $4 million. Neither route requires a monthly principal-and-interest payment while you live in the home with taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Los Angeles picture
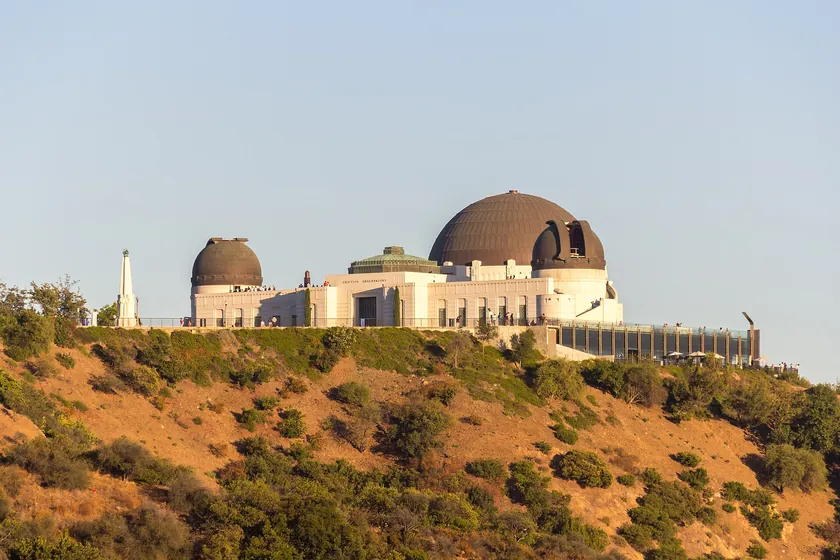
Los Angeles is really a dozen housing markets wearing one name. A 1950s ranch in Sherman Oaks or Woodland Hills, a Spanish bungalow in Cheviot Hills, a view lot above Silver Lake: these homes were often bought decades ago for a fraction of what they carry today, and Proposition 13 has kept the tax bill low enough that the owners never left. The result is a generation of Angelenos who are house-rich on paper and squeezed in practice: the equity is enormous, but the pension, Social Security, or fixed income has not kept pace with the cost of living here.
The citywide Zillow average sits near $928,000, but that number hides the spread. In much of the San Fernando Valley and the Eastside, values fall under the 2026 FHA HECM lending limit of $1,249,125, which means the federally insured program can reach a meaningful share of the home’s value. On the Westside, in the hills, and along the coast, values run past the limit, and that is exactly where proprietary jumbo programs, with lending to $4 million and eligibility starting at age 55, were built to work.
What I see most often in L.A. files: eliminating an existing mortgage payment that was refinanced one time too many, establishing a growing standby line of credit as a buffer against sequence-of-returns risk in a retirement portfolio, and helping one spouse keep the family home after a gray divorce without a payment a single income can’t carry.
Ideal Financial’s licensed office is in Torrance, in Los Angeles County, and I serve homeowners across the county and the City of Los Angeles. Most clients work with me by phone or video.
What 177 Los Angeles files actually look like
The three busiest ZIP codes in the past year were 90047, 90043, and 90044: Vermont Knolls, the blocks toward View Park, and Athens. Thirty-eight loans were insured there and only one touched the ceiling, on typical values from about $642,000 to $809,000. These are owners who bought decades ago, paid faithfully, and are now converting a paid-down house into a cushion. That is the exact borrower the FHA program was designed around, and the records show it working.
In 90039 and 90068, Silver Lake’s slopes and the Hollywood Hills, typical values run past $1.3 million and 8 of 13 insured loans reached the ceiling. A capped HECM is not a dead end, but it means the calculation ignores every dollar above $1,249,125, so on these streets the proprietary comparison is not optional. I quote the two side by side and let the spread argue for itself.
A Valley ranch in Reseda and a Spanish duplex near USC are different files: different values, different title histories, sometimes a 2-to-4-unit building with a tenant in place. The 89 loans HUD recorded outside the top five ZIP codes were spread across 46 more, which is to say there is no single Los Angeles playbook. I read the deed and the numbers before I recommend a program, not after.
How each program fits Los Angeles
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Los Angeles home lands; your own age and value may point elsewhere.
What every Los Angeles borrower must know
Who qualifies: age 62 and up for the FHA HECM, and from 55 on several proprietary jumbo programs that matter in this county more than most. The Los Angeles home must be your primary residence, the equity real, and the financial assessment has to show the obligations below fit your budget. Every HECM starts with independent counseling from a HUD-approved agency you pick yourself off the federal roster (national line: 800-569-4287); California then adds its own protections, including a cooling-off period before you are committed.
What stays on you: the Los Angeles County property tax bill in full, every direct assessment included, plus homeowner’s insurance, HOA dues where they apply, and genuine upkeep. Meet those and no monthly mortgage payment is required for as long as you live in the home; let them slide and the loan can be called due. When the budget is tight I build a set-aside that pays taxes and insurance automatically, which is often what makes the file safe.
What protects you: the deed stays in your name or your living trust. The loan is non-recourse, meaning the payoff can never exceed what the home is worth when it is repaid, and anything left over when the home sells belongs to you or your heirs, never the lender.
Many long-tenure Los Angeles owners are protected by a Proposition 13 tax base far below today’s value. A reverse mortgage does not disturb that assessment; you are borrowing against the home, not selling it. And if you do eventually move within California, Proposition 19 lets homeowners 55 and over transfer that low base-year value to a replacement home up to three times.
Choosing a reverse mortgage broker in Los Angeles
Los Angeles has no shortage of people who will quote you a reverse mortgage: brokers, direct lenders, and websites that collect your details and sell them. The loan underneath is usually the same federal HECM. What differs is the person you work with. Four checks before you decide, whoever you talk to, including me:
- Look up the license. Every mortgage broker and loan officer is listed on NMLS Consumer Access, and California brokers on the Department of Real Estate license lookup. Check the person and the company, and look for any disciplinary action.
- Expect the counseling, and choose the counselor yourself. A HECM requires a session with an independent HUD-approved counselor before you apply, and California then requires seven days before a lender may take a final application or charge any fee. Anyone who rushes you past either one is a reason to stop.
- Get the costs in writing, side by side. Ask for the HECM and, where your home’s value calls for it, a proprietary jumbo, each with the amount available, every cost, and what arrives at closing, before you apply. Then compare quotes line by line. What each cost is →
- Ask who handles the file. Find out whether the person quoting you is the person who will take the file to closing, or whether it goes to someone you have not met.
The full checklist, with eight questions to ask and the red flags to walk away from, is on how to choose a reverse mortgage broker.
Los Angeles questions, straight answers
My home is in the hills and worth well over the HECM limit. Am I stuck?
No. The FHA HECM calculates proceeds using its 2026 lending limit of $1,249,125 even on higher-value homes, but proprietary jumbo reverse programs lend against values up to $4 million and start at age 55 rather than 62. For most higher-value Los Angeles homes, the jumbo comparison is the first thing I run.
I refinanced during the low-rate years and still owe quite a bit. Does that rule me out?
Not necessarily. The existing loan is paid off through the reverse mortgage at closing; what matters is whether the available proceeds cover the payoff. With L.A.’s equity positions, they often do, and eliminating that monthly payment is the single most common reason my Los Angeles clients call.
Will a reverse mortgage change my Prop 13 property taxes?
No. Your assessed value and tax base are unchanged, because you still own the home and title stays in your name (or your trust). You must continue paying the property taxes themselves; that is a condition of every reverse mortgage.
Can I keep the home in our family trust?
Generally yes. HECM and the jumbo programs I arrange routinely close in revocable living trusts, which most of my Los Angeles clients have. I review the trust with the lender early in the file so there are no surprises.
The calculator shows me roughly half my home's value. Why not more?
Because the principal limit is set by age and rates, not by generosity. For the typical Los Angeles borrower in the past year it ran about 46% of value: enough to retire a balance or fund a growing line, and deliberately conservative so the non-recourse guarantee holds. Older borrowers calculate higher. I will show you the exact factor for your age rather than a brochure number.
We live in the front unit of our duplex near USC. Does the rental half disqualify us?
No. FHA insures HECMs on 2-to-4-unit properties when one unit is your primary residence, and the appraisal values the whole building. The tenant’s rent can even help the financial assessment. Bring the lease and the tax bill to the first call and I will tell you how the building reads on paper.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
Los Angeles files raise the same next questions again and again; each has its own page:
- What a reverse mortgage actually costs: every cost category in dollars, what gets financed, and how to decode a “no cost” pitch.
- HECM line of credit compared with a bank HELOC: the growing line against the freezable one, priced honestly for LA equity.
- The reverse mortgage glossary: the disclosure vocabulary, from principal limit factor to LESA, in plain words.
- Who qualifies for a reverse mortgage: the six tests, including the 2-to-4-unit and condo rules this city uses constantly.
- How reverse mortgage rates work: index plus margin, the expected rate, and how a quote should be compared.
- Helping a parent decide: what adult children should understand before Mom signs anything.
For the hillside and Westside homes the FHA calculation cannot fully count, jumbo reverse mortgages for California homes is the page to read first.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Los Angeles numbers.
One call puts your Los Angeles number in writing: HECM column, jumbo column, and the do-nothing comparison.
- A call back within minutes during California business hours
- Your ZIP code’s actual record, not a citywide average
- If neither column beats doing nothing, I say that too
Rather talk it through now?
Tell me the neighborhood, the ages, and what the money is for. Los Angeles runs more of these files than any city in the state, and the ones that go well start with somebody pricing both programs instead of selling one.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide