Reverse Mortgage Broker Serving Glendale, California
In Glendale, the house is often the family’s anchor — sometimes for three generations under one roof. A reverse mortgage can steady the finances of the owners without disturbing the household everyone depends on.
Five of seven at the ceiling: Glendale quotes run high.
FHA endorsement records are public down to the loan. What follows is the September 2025 through August 2026 ledger for Los Angeles County and for Glendale specifically.
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Glendale itself | 7 |
| Glendale: reached the ceiling | 5 of 7 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
For scale: Los Angeles County’s past-year endorsements reached the FHA ceiling 21% of the time. A percentage like that describes the recorded loans, not your options; what it earns is a two-program quote on every Glendale call.
Glendale itself recorded just seven insured loans in the past year, five at the ceiling. Seven is a raw count, not a trend, but five of seven capped fits what the hillsides already suggest: this city’s values push hard against the federal limit.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Glendale by ZIP code
Glendale’s nine ZIP codes with the past year’s recorded HECMs and typical values: six land under the 2026 limit, three above it, Verdugo flats to canyon.
Glendale HECMs insured in the past year
Of the 9 Glendale ZIP codes, 6 have a typical value under the $1,249,125 limit and 3 are over it; typical values run from about $766,000 to $1.7 million. The most loans were in 91206: 3 of the 7. Of the 7 loans, 5 reached the FHA ceiling, so the jumbo comparison matters here.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 91201 | 1 | 0 | $1,276,000 | Over |
| 91202 | 1 | 1 | $1,198,000 | Under |
| 91203 | 0 | 0 | $781,000 | Under |
| 91204 | 0 | 0 | $766,000 | Under |
| 91205 | 0 | 0 | $858,000 | Under |
| 91206 | 3 | 3 | $1,116,000 | Under |
| 91207 | 0 | 0 | $1,690,000 | Over |
| 91208 | 1 | 1 | $1,506,000 | Over |
| 91210 | 0 | 0 | $1,164,000 | Under |
All 7 HECMs HUD recorded with a Glendale address; one of them carried a ZIP code Zillow does not assign to Glendale, so it is not in the table. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 4 FHA-approved condominium projects with a Glendale mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Glendale loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Glendale bottom line: a typical value near $1,173,000 sits close under the 2026 HECM maximum claim amount of $1,249,125, so the flats still calculate at full value in the FHA program for owners 62 and older, while Rossmoyne, Verdugo Woodlands, and the view streets above Glenoaks, and any owner aged 55 to 61, get their real answer from proprietary jumbo programs on values to $4 million. In both, living in the home with taxes, insurance, and maintenance current means no monthly principal-and-interest payment is required.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Glendale picture
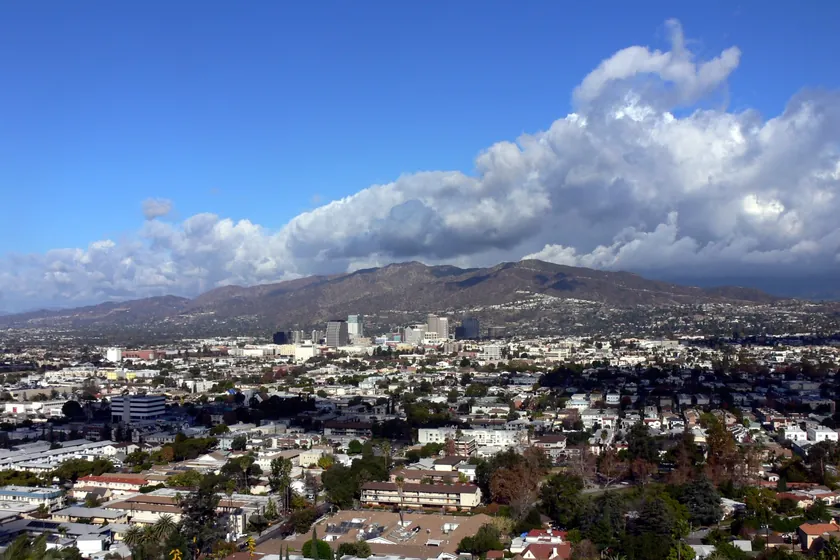
Glendale’s hillside neighborhoods (Rossmoyne, Adams Hill, Verdugo Woodlands, the Chevy Chase canyon) carry a citywide average value near $1,173,000, comfortably beneath the 2026 FHA HECM limit of $1,249,125. Like neighboring Pasadena, this is a run-both-calculations city: the HECM still reaches full value on much of the housing stock, while the view homes above Glenoaks push into jumbo territory, where proprietary programs lend to $4 million from age 55.
What makes Glendale files distinctive in my practice is the household itself. Multigenerational living is common here, and a reverse mortgage is built to accommodate it: adult children and grandchildren can continue living in the home; the occupancy requirement applies to the borrowers, who must keep the home as their primary residence. I’ve structured files where the loan eliminated the parents’ mortgage payment precisely so the household’s combined budget could redirect toward a grandchild’s education.
One thing I’ll say plainly, because Glendale families ask it plainly: the bank does not take the house. Title stays in your name or your trust. The loan is repaid when the last borrower permanently leaves the home, typically by the family selling or refinancing, and both HECM and the jumbo programs I arrange are non-recourse, so neither you nor your heirs can owe more than the home is worth.
The Glendale patterns worth knowing
Every one of the three loans HUD recorded in 91206 in the past year reached the ceiling. That ZIP climbs from the Chevy Chase corridor into the canyon, where lots and views price the houses past $1.5 million even when the tax roll remembers them smaller. On those streets I open with the jumbo column and let the HECM argue its way back in, usually on the strength of the growing credit line.
Above Glenoaks and into the Verdugos, brush-zone ratings and FAIR Plan placements are increasingly the insurance reality. A reverse mortgage does not forbid any of that; it requires the coverage exist and keep getting paid, and the financial assessment wants the premium to fit the budget. I price the file with the real premium from day one, because pretending insurance costs what it did in 2019 helps nobody.
Glendale households often hold three generations, and the worry I hear is losing the house the family runs on. The mechanics are friendlier: a reverse mortgage leaves title with the owners, lets adult children keep living there, and at the end the family chooses, refinance the balance, or sell and keep the difference. The loan funds staying put; it does not schedule anyone’s departure.
How each program fits Glendale
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Glendale home lands; your own age and value may point elsewhere.
What every Glendale borrower must know
Who qualifies: 62-plus for the federally insured HECM; proprietary jumbo programs start at 55 and do a lot of Glendale’s work. The home must be the primary residence with substantial equity, and the financial assessment must show room for the obligations below. Before any HECM comes independent counseling through a HUD-approved agency of your choosing from the federal roster (national line: 800-569-4287), with California’s cooling-off period after.
Still yours to pay: property taxes with every line the county adds, homeowner’s insurance at hillside rates where they apply, HOA dues if any, and the maintenance a canyon lot actually needs. Current on these, you owe no monthly mortgage payment while the home is yours to live in; behind on them, the loan can be called due. A set-aside that automates taxes and insurance is cheap certainty, and I use it often here.
What protects you: title never leaves you or your trust. The non-recourse rule caps what can ever be owed at the home’s value, protecting children as well as borrowers, and all equity beyond the payoff stays with the family.
Glendale owners frequently plan around the family, not just the individual, and California’s Proposition 19 changed the rules for passing a home to children. Keeping the parents’ low tax base now generally requires a child to occupy the home as their principal residence, within limits. A reverse mortgage doesn’t change any of that; it neither triggers reassessment nor transfers title. But if generational transfer is part of your plan, your estate attorney and I should be in the same conversation.
Glendale questions, straight answers
My adult children live with us. Does that affect eligibility?
No. The occupancy rule applies to the borrowers: you must live in the home as your primary residence. Family members living with you are not a problem, and nothing about the loan requires them to leave. What they cannot do is remain in the home indefinitely after the last borrower permanently leaves; at that point the loan comes due and the family typically sells or refinances.
If we take a reverse mortgage, can we still leave the house to the kids?
Yes. Your heirs inherit the home subject to the loan balance, like any mortgage. They can keep it by paying off the balance (for HECMs, at the lesser of the balance or 95% of appraised value) or sell it and keep the remaining equity. The loan is non-recourse, so they can never owe more than the home is worth.
Our home is on the hill with a view and worth more than the FHA limit. Options?
That’s jumbo territory, and it’s a strength, not a problem: proprietary programs lend against values to $4 million, begin at age 55, and carry no FHA mortgage insurance premium. I’ll run it against the HECM so you see both.
Do both spouses have to be on the loan?
Both spouses should always be addressed in the structure. A younger spouse can be a co-borrower (jumbo programs start at 55) or, on a HECM, an eligible non-borrowing spouse with protections that allow them to remain in the home. This is one of the most important details in any file, and I put it in writing before you commit to anything.
Our hillside home is on the FAIR Plan with a wrap-around policy. Will the cost sink us?
It gets counted, not punished. The assessment asks whether taxes, insurance, and living costs fit your income and assets; a four-figure premium tightens that math but rarely breaks it when there is real equity. Where it is close, a set-aside carved from proceeds pays the premiums automatically and satisfies everyone.
Our son is on title with us. Does he have to come off?
If he will not be a borrower, yes, typically before closing, and it deserves a family conversation first because a non-borrower on title has rights worth understanding. A spouse under 62 is different: there are protected non-borrowing-spouse rules that keep her in the home. Which situation you have determines the paperwork, so say so at the start.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
After the Glendale numbers, these are the pages people open next:
- What a reverse mortgage actually costs: dollars, not adjectives: origination to servicing, and what rides in the loan.
- HECM line of credit compared with a bank HELOC: the line that grows versus the line that freezes, for fixed incomes.
- The reverse mortgage glossary: disclosure language decoded, LESA and principal limit factor included.
- Who qualifies for a reverse mortgage: the six requirements plus the title and non-borrowing-spouse rules.
- How reverse mortgage rates work: index, margin, expected rate: the three numbers behind every quote.
- Helping a parent decide: what the kids should ask before the parents sign.
For view homes the federal calculation cannot fully reach, start at jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Glendale numbers.
One short call, and your Glendale quote arrives in writing with both programs priced.
- A call back within minutes during California business hours
- Real hillside insurance figures in the math, not placeholders
- If waiting serves you better, that is the advice
Rather talk it through now?
Tell me where in Glendale the house sits and who lives in it. Five of seven files here ran into the federal ceiling in the past year, which is exactly why the first quote you see from me has two columns on it.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide