Reverse Mortgage Broker Serving Simi Valley, California
Simi Valley filled up in the 70s and 80s with families chasing a yard and a safe street — many of them never left. Forty years of staying put built equity that can now retire the mortgage payment for good.
One capped loan in fifteen: the valley fits the federal box.
Each month HUD publishes the loan-level file of every FHA reverse mortgage it insures. The Ventura County and Simi Valley entries below cover September 2025 through August 2026.
| HECMs insured by FHA, Ventura County | 114 |
| Of those, purchases (HECM for Purchase) | 4 |
| Reached the FHA ceiling | 14.0% |
| In Simi Valley itself | 15 |
| Simi Valley: reached the ceiling | 1 of 15 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Around Ventura County, 14% of the reverse mortgages FHA insured in the past year reached the ceiling. Useful context, zero authority over your address: the quote still runs both columns, because that is what the spread in this county demands.
Simi Valley’s fifteen insured loans tell a quieter story: one reached the ceiling, fourteen did not. Small sample, clear tilt. On these tracts the federal program usually counts the entire house.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Simi Valley by ZIP code
Two ZIP codes, nearly twin values: 93063 and 93065 both type out around $830,000, far under the 2026 limit. The past year’s recorded loans:
Simi Valley HECMs insured in the past year
Both Simi Valley ZIP codes have a typical value of about $829,000 to $831,000, under the $1,249,125 limit. The most loans were in 93063: 8 of the 15.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 93063 | 8 | 0 | $829,000 | Under |
| 93065 | 7 | 1 | $831,000 | Under |
All 15 HECMs HUD recorded with a Simi Valley address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 10 FHA-approved condominium projects with a Simi Valley mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Simi Valley loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
Simi Valley in one paragraph: with the citywide average value near $830,000 (the two ZIP codes type out at $829,000 and $831,000) against a 2026 HECM maximum claim amount of $1,249,125, the FHA program works with essentially the full house for owners 62 and older, and the records agree, one capped loan out of fifteen in the past year. Jumbo programs to $4 million serve the rare estate parcel and owners aged 55 to 61. Either way, living in the home with taxes, insurance, and upkeep current means no monthly principal-and-interest payment is required.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Simi Valley picture
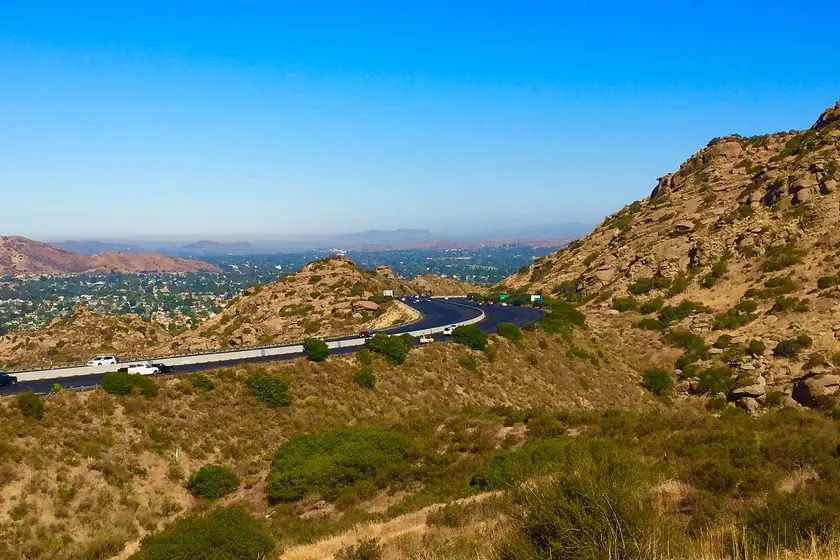
Simi Valley’s citywide average value of roughly $830,000 sits well under the 2026 FHA HECM limit of $1,249,125, which makes this one of Ventura County’s cleanest HECM markets: the program calculates against the home’s full value across nearly all of the city’s neighborhoods, from the original east-end tracts to Wood Ranch.
The tenure here is remarkable. I regularly meet Simi owners who bought for under $100,000 when the aerospace field lab on the hill was still running and the 118 was new, and who now hold three-quarters of a million dollars of equity alongside a fixed income that has to be stretched carefully. That is precisely the imbalance a reverse mortgage corrects: it converts a portion of the locked-up equity into eliminated payments, a growing credit line, or monthly draws, while you keep living in the same house on the same cul-de-sac.
Simi also has one of the stronger cases in the county for the eliminate-the-payment file: owners who refinanced during the cash-out years and carried the payment into retirement. When available proceeds cover the payoff, the required monthly payment ends at closing, and for a household running on Social Security plus a pension, that single change often rebalances the entire monthly budget.
Three Simi Valley files I see on repeat
Two ZIP codes, two dollars apart in typical value: Simi is the most uniform market on my whole service list, and uniformity is quietly valuable in this business. Appraisals bracket cleanly, comps are plentiful, and the quote I give you over the phone survives the appraisal more often here than nearly anywhere. Fewer surprises is a real feature, not a small one.
Plenty of valley owners refinanced during the loose years and still carry a balance into retirement. A common Simi file uses the HECM to retire that balance entirely: the required monthly principal-and-interest payment disappears, and the budget breathes again. The trade is that the balance accrues instead of amortizing, which I put in writing, in dollars, before anyone decides.
Wood Ranch brings HOA dues into the obligation math; the east end’s original tracts bring sixty-year-old roofs and galvanized plumbing into the appraisal. Both are manageable with the same tool kit, dues counted in the assessment, repairs funded by set-aside at closing, as long as they are named at the start rather than discovered in escrow.
How each program fits Simi Valley
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Simi Valley home lands; your own age and value may point elsewhere.
What every Simi Valley borrower must know
Who qualifies: homeowners 62 and older for the FHA HECM (jumbo alternatives open at 55, though Simi values seldom need them), occupying the home as the primary residence, with real equity and a financial assessment that shows the obligations below are sustainable. Counseling with a HUD-approved agency you select from the federal roster comes first (national line: 800-569-4287), followed by California’s cooling-off period.
What stays on your ledger: the Ventura County tax bill complete with assessments, homeowner’s insurance, Wood Ranch or other HOA dues where they apply, and honest maintenance on houses now in their fifth and sixth decades. Keep those current and no monthly mortgage payment is required while you live in the home; fall behind and the loan can be called. Set-asides exist precisely to make that risk boring, and I use them readily.
What protects you: the deed remains in your name or your trust. Non-recourse means the debt can never pass the home’s value at repayment, whoever is doing the repaying, and any equity above the balance goes to you or your heirs, not the lender.
Four decades of Prop 13 protection means many Simi owners pay taxes on a small fraction of today’s value, and a reverse mortgage doesn’t disturb that assessment. And for the owners eyeing a move closer to grandchildren elsewhere in California, Proposition 19 lets the low base travel with you; paired with a HECM for Purchase, the move needn’t create a payment.
Simi Valley questions, straight answers
We bought in 1982 and owe nothing. Why would we borrow now?
Free-and-clear owners are often my best-fit clients, not because they must borrow, but because a standby line of credit costs little to hold, grows every year, and stands ready for the roof, the care need, or the market downturn. Opening it while you're younger and rates make the math favorable is what gives it time to grow.
Will this affect our Social Security or Medicare?
No: both are non-means-tested, and reverse mortgage proceeds are borrowed funds, not income. Needs-based programs (SSI, Medi-Cal) can be affected by how proceeds are held from month to month, and if that applies to you we plan for it deliberately with your benefits counselor.
What are our heirs actually signing up for?
A defined, protected outcome: they inherit the home subject to the balance, can keep it by paying the balance off (on a HECM, capped at 95% of appraised value), or sell and keep the remaining equity. The loan is non-recourse. I encourage adult children to sit in on the process; it makes everyone’s life easier later.
Our home needs a roof before winter. Does that stop us?
Usually not. If the appraisal flags it, we handle it with a repair set-aside funded from the loan itself, or complete the work before closing. Don’t pre-spend savings on the assumption you must. Call first and let’s sequence it correctly.
We're still sending $1,900 a month at 3 percent. Doesn't keeping that rate beat everything?
Not automatically. The 3 percent describes the balance’s cost; it says nothing about the $22,800 a year leaving your budget. If cash flow is the strain, eliminating the required payment can outweigh the rate math, and if it is not, I will tell you to keep the loan you have. That comparison belongs on paper, and it is exactly what the first call produces.
The roof has a solar lease on it. Problem?
A manageable one. Leased systems carry a UCC filing that must be addressed, and the leasing company signs familiar paperwork; owned panels are simpler still. Payments on a lease fold into the budget review. Bring the lease terms to the first call and the file is sequenced around them from day one.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
Where Simi Valley readers usually go next:
- What a reverse mortgage actually costs: category-by-category dollars, including what the loan can absorb.
- HECM line of credit compared with a bank HELOC: the retirement-budget comparison, payments and freeze risk included.
- The reverse mortgage glossary: disclosure vocabulary in plain English, A to Z.
- Who qualifies for a reverse mortgage: six requirements, from age and equity to the financial assessment.
- How reverse mortgage rates work: what moves proceeds: index, margin, and the expected rate.
- Helping a parent decide: for sons and daughters weighing the family house and the loan.
Should an appraisal surprise past the federal line, the route is jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Simi Valley numbers.
Fifteen minutes puts the Simi Valley numbers in front of you: payoff, line of credit, and the keep-what-you-have option.
- A call back within minutes during California business hours
- The 3-percent-mortgage comparison, written out in dollars
- Advice that includes keeping the loan you already have
Rather talk it through now?
Tell me which end of the valley, what is still owed, and what the monthly budget needs. Simi’s records say the program fits here; whether it beats standing pat is your arithmetic, and I will show both columns without leaning on either.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide