Reverse Mortgage Broker Serving Thousand Oaks, California
The Conejo Valley promised space, schools, and a slower pace, and a generation of owners in Lynn Ranch, Wildwood, and the older Thousand Oaks tracts collected on all three. The equity they built along the way is the quiet fourth asset.
Six of fifteen at the ceiling in a three-ZIP city.
FHA endorsements are public records, published monthly. Here is the Ventura County and Thousand Oaks ledger across the twelve releases from September 2025 through August 2026.
| HECMs insured by FHA, Ventura County | 114 |
| Of those, purchases (HECM for Purchase) | 4 |
| Reached the FHA ceiling | 14.0% |
| In Thousand Oaks itself | 15 |
| Thousand Oaks: reached the ceiling | 6 of 15 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Ventura County’s past-year record: 14% of insured loans reached the FHA ceiling, 86% did not. A county rate is a planning backdrop, nothing more; the house on the appraisal is the only one that matters, so I quote both programs and let yours pick.
Thousand Oaks itself produced 15 insured loans, six at the ceiling. Fifteen is a count to read, not a rate to project, and what it reads like is the Conejo Valley: mostly under the limit, with North Ranch and the view streets pressing past it.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Thousand Oaks by ZIP code
Three ZIP codes cover the city, every one with a typical value under the 2026 limit. The recorded HECMs and values, from Newbury Park’s border to Westlake’s edge:
Thousand Oaks HECMs insured in the past year
All 3 Thousand Oaks ZIP codes have a typical value under the $1,249,125 limit, from about $1,000,000 to $1,183,000. The most loans were in 91360: 8 of the 15. Even so, 6 of the 15 loans reached the FHA ceiling: a typical value is the middle of the market, not every house.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 91320 | 2 | 0 | $1,002,000 | Under |
| 91360 | 8 | 4 | $1,000,000 | Under |
| 91362 | 5 | 2 | $1,183,000 | Under |
All 15 HECMs HUD recorded with a Thousand Oaks address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 8 FHA-approved condominium projects with a Thousand Oaks mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Thousand Oaks loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The short version for Thousand Oaks: typical Conejo values near $1,028,000 sit under the 2026 HECM maximum claim amount of $1,249,125, keeping the federally insured program at full strength for owners 62 and older, while North Ranch, the open-space view lots, and owners aged 55 to 61 route to proprietary jumbo programs on values to $4 million. Whichever applies, there is no required monthly principal-and-interest payment while you live in the home and keep taxes, insurance, and maintenance current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Thousand Oaks picture
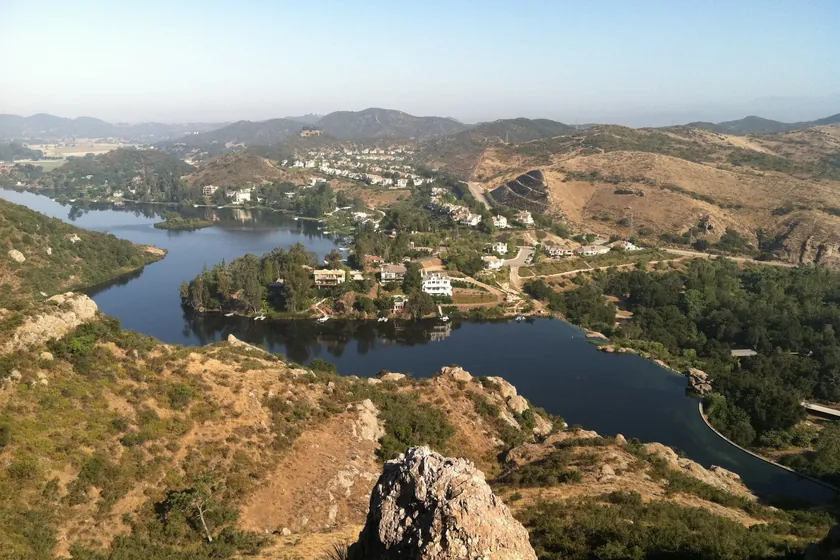
Thousand Oaks averages about $1,028,000 by Zillow’s index, placing the typical Conejo Valley home under the 2026 FHA HECM limit of $1,249,125 (full-value territory for the federally insured program), while the estates of North Ranch and the view properties toward the Santa Monica Mountains cross into jumbo range, served by proprietary programs to $4 million from age 55.
This valley has an unusually deep bench of professional retirees: decades of careers at the biotech campus and the corporate offices along the 101 corridor. These are clients who arrive with an advisor, a trust, and questions about sequence-of-returns risk, and the standby HECM line of credit answers them well: a growing, non-market source of funds to draw in down years so the portfolio isn’t sold at the bottom.
The other Conejo conversation is single-level living. The valley’s beloved ranch homes are ideal for aging in place, and its two-stories are ideal candidates for a right-sizing move that stays local. Either way, funding a stay-put plan with a line of credit or financing the move with a HECM for Purchase, the goal is the same: keep the Conejo life without carrying a mortgage payment into it.
Reading the Conejo Valley records
Eight of the city’s fifteen insured loans in the past year sat in 91360, and four of the eight reached the ceiling, on a ZIP whose typical value is almost exactly $1,000,000. Same streets, opposite outcomes: the midpoint says HECM, the nicer corner lot says jumbo. That is why a Thousand Oaks quote from me never leans on the citywide average.
Conejo retirements tend to be planned ones: pensions, 401(k)s, an advisor on speed-dial. The HECM’s role in that picture is usually not spending money, it is the standby credit line that grows every year it goes untouched, so a bad market year gets funded from the house instead of from selling shares at the bottom. I coordinate with your advisor directly when you want the strategies aligned.
The third recurring file is the two-story in Wildwood traded for single-level near the Oaks: a HECM for Purchase funds the new home with roughly 55 to 70 percent down depending on age, no required monthly principal-and-interest payment after, and Proposition 19 carries the old tax base across town. The equity stays in Thousand Oaks; the stairs do not.
How each program fits Thousand Oaks
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Thousand Oaks home lands; your own age and value may point elsewhere.
What every Thousand Oaks borrower must know
Who qualifies: 62 and up for the FHA HECM, 55 and up on the proprietary side that serves North Ranch. The home must be your primary residence with genuine equity, and the financial assessment confirms the obligations below fit your retirement budget. A HUD-approved counseling session, agency chosen by you from the federal roster (national line: 800-569-4287), comes before any HECM, and California adds a cooling-off period after signing.
Still your responsibility: Ventura County property taxes with every assessment, homeowner’s insurance, HOA dues across much of the Conejo’s planned stock, and upkeep befitting the home. Keep them current and no monthly mortgage payment is required while you live there; neglect them and the loan can be called due. A set-aside automating taxes and insurance is a standard belt I add whenever the budget runs narrow.
What protects you: title stays with you or your living trust, exactly as now. Federal non-recourse insurance caps any payoff at the home’s value, insulating both spouses and heirs, and all equity beyond the balance remains the family’s at sale.
Ventura County owners who bought in the 70s–90s often hold Prop 13 assessments far below today’s value; a reverse mortgage leaves the assessment untouched. Proposition 19 base-year transfers work here exactly as elsewhere in California for owners 55+, including moves within the county, which is what most of my Conejo clients actually want.
Thousand Oaks questions, straight answers
We have a solid portfolio. Why would our advisor support a reverse mortgage?
Because the peer-reviewed research supports the standby strategy: opening a HECM line of credit early and drawing from it in market-down years measurably improves portfolio survival rates versus selling depressed assets. I provide the published studies to your advisor directly; several of my best referral relationships started as skeptics.
Our home backs to open space and is worth more than the FHA limit. What then?
Then we compare the HECM, which caps its calculation at the $1,249,125 limit, against a jumbo program that uses your full value up to $4 million, with no FHA insurance premium and eligibility from 55. In North Ranch and the view corridors, the jumbo frequently wins.
Is the money from a reverse mortgage taxable?
Loan proceeds are not income; they are borrowed funds, so they are not taxed as income and do not by themselves affect Social Security or Medicare. Needs-based programs like SSI or Medi-Cal are different and depend on how funds are held; that's a conversation for your tax professional, and I'll coordinate with them.
How long does the process take?
Plan on roughly 30–45 days from counseling to closing when the file is clean. California adds its own consumer protections, including a required cooling-off period. You cannot be rushed, and I would not let you be anyway.
Our living trust dates to 1998. Does it need work before the loan?
Probably light work. Lenders review the trust (or a California certification of trust) to confirm it permits encumbering the home; older documents sometimes want an amendment or restatement first. It is days of work with your estate attorney, not months, and I flag it in the first week so it never holds escrow hostage.
If home values slide, can the line of credit be cut?
No. That is the HECM’s sharpest difference from a bank HELOC: once established, the line cannot be frozen or reduced for market reasons, and its unused balance keeps growing regardless of what Zillow says. In a soft year that guarantee is precisely what the standby strategy is buying.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The pages Thousand Oaks readers open after this one:
- What a reverse mortgage actually costs: real dollars by category, and what financing the costs changes over time.
- HECM line of credit compared with a bank HELOC: the standby question settled: growth and no freezes versus bank discretion.
- The reverse mortgage glossary: every term your disclosures will use, defined without fog.
- Who qualifies for a reverse mortgage: the six requirements and the trust and spouse-age rules in detail.
- How reverse mortgage rates work: expected rate mechanics, and why the margin deserves scrutiny.
- Helping a parent decide: the children’s guide to houses, inheritances, and good questions.
North Ranch and the view properties that will appraise past the limit start at jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Thousand Oaks numbers.
One call returns your Thousand Oaks arithmetic in writing, standby line included, both programs priced.
- A call back within minutes during California business hours
- Advisor-ready figures you can forward as-is
- A straight no whenever the plan beats the product
Rather talk it through now?
Bring the address, the ages, and the retirement plan already in motion. In the Conejo the question is rarely whether the equity exists; it is whether the house or the portfolio should fund the next decade, and that answer deserves arithmetic, not adjectives.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide