Reverse Mortgage Broker Serving Santa Clarita, California
Valencia, Saugus, Newhall, Canyon Country: families moved up the 5 for a bigger house and a better price, and the valley delivered on both. Now the house can deliver one more time: a retirement with no required monthly mortgage payment, as long as the taxes, insurance and upkeep stay current.
Seven ZIP codes, every one under the federal limit.
Every FHA reverse mortgage lands in HUD’s public endorsement file. The table below is Los Angeles County and Santa Clarita as those records stood across September 2025 through August 2026.
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Santa Clarita itself | 25 |
| Santa Clarita: reached the ceiling | 4.0% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Los Angeles County as a whole saw 21% of its past-year endorsements reach the FHA ceiling. That figure describes recorded loans, not your valley; its real use is as the reason every quote I write prices both programs.
Santa Clarita’s own share was 25 insured loans with just 4.0% at the ceiling, a fraction of the county rate. Up here the federal program almost always gets to work with the whole house.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Santa Clarita by ZIP code
Seven ZIP codes cover the valley, Newhall to Castaic’s edge, and all seven carry typical values below the 2026 limit. The past year’s recorded HECMs, ZIP by ZIP:
Santa Clarita HECMs insured in the past year
All 7 Santa Clarita ZIP codes have a typical value under the $1,249,125 limit, from about $681,000 to $907,000. The most loans were in 91350: 8 of the 25.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 91321 | 2 | 0 | $681,000 | Under |
| 91350 | 8 | 0 | $804,000 | Under |
| 91351 | 5 | 0 | $705,000 | Under |
| 91354 | 3 | 0 | $830,000 | Under |
| 91355 | 4 | 1 | $777,000 | Under |
| 91387 | 1 | 0 | $800,000 | Under |
| 91390 | 2 | 0 | $907,000 | Under |
All 25 HECMs HUD recorded with a Santa Clarita address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 11 FHA-approved condominium projects with a Santa Clarita mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Santa Clarita loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Santa Clarita bottom line: with typical values near $786,000 and every ZIP code under the 2026 HECM maximum claim amount of $1,249,125, the FHA program calculates against essentially full value across the valley for owners 62 and older. Jumbo programs to $4 million exist for the estate properties and for owners aged 55 to 61, but they are the exception here, not the rule. Either way, no monthly principal-and-interest payment is required while you occupy the home with taxes, insurance, and maintenance current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Santa Clarita picture
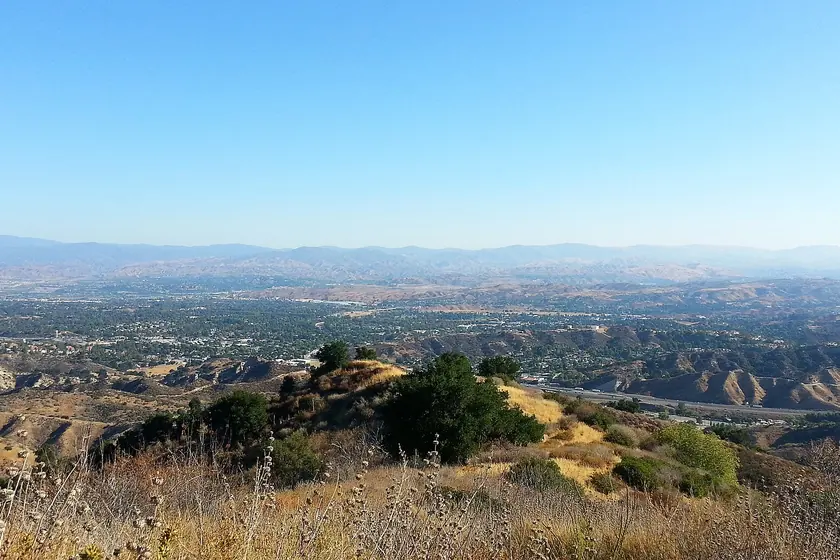
Santa Clarita is a textbook HECM market. The citywide average value near $786,000 sits well below the 2026 FHA lending limit of $1,249,125, so the federally insured program works with the full value of virtually every home in the valley, from the original Valencia master-plan neighborhoods to the newer tracts up Plum Canyon. When the whole value counts, the proceeds calculation is at its most efficient.
The SCV pattern I see constantly: owners in their 60s who bought in the 1980s or 90s, refinanced along the way, and still carry a payment into retirement. Eliminating that payment is the single most common outcome I deliver here: the loan pays off the existing mortgage at closing, and the monthly obligation shifts to the things you must keep current anyway: property taxes, insurance, upkeep, and yes, the HOA. Santa Clarita is HOA country, and HOA dues are one of the obligations a reverse mortgage borrower must maintain; I underline it in every SCV file.
The valley also has a genuine 55+ anchor in Friendly Valley, and right-sizing is a live topic across SCV as the big two-story becomes more house than anyone needs. A HECM for Purchase lets you move to single-level, here or anywhere in California, putting roughly 55 to 70 percent down from your sale proceeds, depending on age, and financing the rest with no required monthly principal-and-interest payment.
How the valley actually uses this loan
91350 led the city with 8 of its 25 insured loans in the past year: Bouquet Canyon tracts and Seco Canyon cul-de-sacs where families bought in the eighties and nineties and stayed. Typical value there is about $804,000, far under the limit, so the program counts the whole house, and none of the eight came near the ceiling.
Plum Canyon, Five Knolls, and the newer west-side tracts carry community-facilities assessments that survive any mortgage payoff: they ride the tax bill, and the tax bill is one of the obligations a reverse mortgage requires you to keep current. The honest move is to put the full bill, Mello-Roos included, into the assessment arithmetic on day one, with a set-aside when the margin is thin.
The classic Santa Clarita file is a couple who fed the 14 or the 5 for twenty-five years, finished the mortgage, and now hold three-quarters of a million dollars of house against Social Security and a modest 401(k). A growing HECM credit line converts that stranded equity into the retirement buffer the commute was supposed to buy, without selling the house the grandkids visit.
How each program fits Santa Clarita
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Santa Clarita home lands; your own age and value may point elsewhere.
What every Santa Clarita borrower must know
Who qualifies: 62 and older for the federally insured HECM, with jumbo programs from 55 for the rare valley property that needs one. The home must be your primary residence, hold real equity, and the financial assessment must show the obligations below fit. HUD-approved counseling comes before any HECM, from an agency you choose off the federal roster (national line: 800-569-4287), with California’s cooling-off period after it.
What you keep paying: the property tax bill with every Mello-Roos and district assessment on it, homeowner’s insurance, the HOA dues most valley tracts carry, and ordinary upkeep. Current on those, you owe no monthly mortgage payment while you live in the home; delinquent, and the loan can be called due. Where the numbers are snug, a tax-and-insurance set-aside inside the loan is the clean answer.
What protects you: title stays yours or your trust’s. The loan is non-recourse, so the payoff can never exceed the home’s value no matter how long you stay, and heirs keep every dollar of equity left after the sale or refinance.
Most Santa Clarita owners bought decades after Prop 13 passed, but the principle still pays: your assessment trails today’s value, and a reverse mortgage doesn’t disturb it. For a move within California, Proposition 19 lets owners 55+ transfer the tax base to a replacement home; pair it with a HECM for Purchase and the right-sizing move keeps both the low taxes and your liquidity.
Santa Clarita questions, straight answers
Does my HOA affect a reverse mortgage?
It doesn’t block one, but it matters twice: HOA dues are an obligation you must keep current for the life of the loan, and on condos the project itself needs FHA approval for a HECM (single-unit approvals are possible). For SCV’s planned single-family communities, it’s simply a budget line we account for honestly.
I still owe $280,000 on my Saugus home. Can a reverse mortgage pay that off?
That’s the most common Santa Clarita file I write. If the available proceeds (based on your age, rates, and value) cover the payoff, the existing loan is retired at closing and the required monthly payment ends. I can tell you in one phone call whether your numbers clear.
Is Friendly Valley eligible?
Friendly Valley units can be, but community structure matters: condominium units need FHA project or single-unit approval for a HECM. Give me the address and I’ll verify the approval status before you spend a dime on anything.
What happens if we outlive the money?
You cannot outlive the loan itself: no payment is required while you live in the home and meet the obligations, regardless of how long that is or what the balance grows to. A tenure-payment HECM can even be structured to pay you monthly for life in the home. And the loan is non-recourse: neither you nor your heirs owe more than the home’s value.
We're in a Mello-Roos tract in Plum Canyon. Those assessments keep going, right?
Right. Community-facilities district charges are part of the tax bill, and the loan requires the whole bill stay current, same as before. What changes is capacity: proceeds or the credit line can be the thing that makes the bill comfortable. I quote with your actual bill, assessments included, never the base rate.
Is refinancing an existing HECM ever worth doing?
Sometimes, and there are federal screens to keep it honest: the new loan must pass benefit tests comparing added proceeds to added costs. A value jump since 2020, a spouse who has since turned 62, or a far better margin can justify it. Bring your last statement and I will run the test honestly, including the answer that you should keep what you have.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
Next questions on most Santa Clarita files, each with its own page:
- What a reverse mortgage actually costs: each cost named in dollars, and the “no cost” sales pitch decoded.
- HECM line of credit compared with a bank HELOC: why the growing, unfreezable line suits a fixed retirement budget.
- The reverse mortgage glossary: disclosure terms in order, from expected rate to LESA.
- Who qualifies for a reverse mortgage: the six requirements, HOA and assessment wrinkles included.
- How reverse mortgage rates work: the margin’s quiet effect on proceeds, explained with numbers.
- Helping a parent decide: a guide for the adult kids down the hill or across the country.
For the Sand Canyon estates and anything else likely to appraise past the limit, jumbo reverse mortgages for California homes covers the alternative.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Santa Clarita numbers.
One call and your Santa Clarita figure is on paper: proceeds, the full tax bill accounted for, and the do-nothing comparison.
- A call back within minutes during California business hours
- Quotes built on your real tax bill, Mello-Roos included
- “Keep what you have” is advice I give regularly
Rather talk it through now?
Tell me the tract, the ages, and the goal, payoff, buffer, or a move to single-level, and you will get valley-specific arithmetic instead of a brochure. The records say Santa Clarita fits this program as cleanly as anywhere in the county; whether it fits your plans is the part we find out together.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide