Reverse Mortgage Broker Serving Pasadena, California
A Craftsman in Bungalow Heaven or a Madison Heights colonial is more than a house; it’s a hundred years of stewardship. A reverse mortgage can fund the next chapter of that stewardship without adding a monthly payment.
Twenty files in a city built before 1930.
The FHA endorsement file is public, loan by loan, month by month. These are the entries for Los Angeles County and for Pasadena across the September 2025 through August 2026 releases.
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Pasadena itself | 20 |
| Pasadena: reached the ceiling | 9 of 20 |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
County context first: 21% of Los Angeles County’s insured reverse mortgages in the past year reached the FHA ceiling. History, not destiny; its only instruction is to run both calculations before trusting either.
Pasadena’s own count was 20 insured loans, nine of them at the ceiling. Twenty loans is too small a sample to turn into a percentage worth planning around, but nine of twenty capped says plainly that this city’s values crowd the federal limit, so the jumbo column earns its place in every quote here.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Pasadena by ZIP code
Pasadena’s six ZIP codes against the 2026 limit, each with its HECMs recorded in the past year and Zillow’s typical value, from the 91101 flats to San Rafael.
Pasadena HECMs insured in the past year
Of the 6 Pasadena ZIP codes, 4 have a typical value under the $1,249,125 limit and 2 are over it; typical values run from about $762,000 to $1.8 million. The most loans were in 91103: 9 of the 20. Of the 20 loans, 9 reached the FHA ceiling.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 91101 | 1 | 0 | $762,000 | Under |
| 91103 | 9 | 3 | $1,072,000 | Under |
| 91104 | 5 | 3 | $1,206,000 | Under |
| 91105 | 0 | 0 | $1,782,000 | Over |
| 91106 | 2 | 1 | $905,000 | Under |
| 91107 | 3 | 2 | $1,303,000 | Over |
All 20 HECMs HUD recorded with a Pasadena address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 10 FHA-approved condominium projects with a Pasadena mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Pasadena loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Pasadena bottom line: a typical Pasadena home around $1,186,000 lands just beneath the 2026 HECM maximum claim amount of $1,249,125, which makes this a genuine two-program city: bungalow blocks calculate at full value under the FHA program for owners 62 and older, while Madison Heights, San Rafael, and the Linda Vista hills, plus any owner aged 55 to 61, belong in the proprietary jumbo conversation on values to $4 million. Both run without a required monthly principal-and-interest payment while taxes, insurance, and upkeep stay current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Pasadena picture
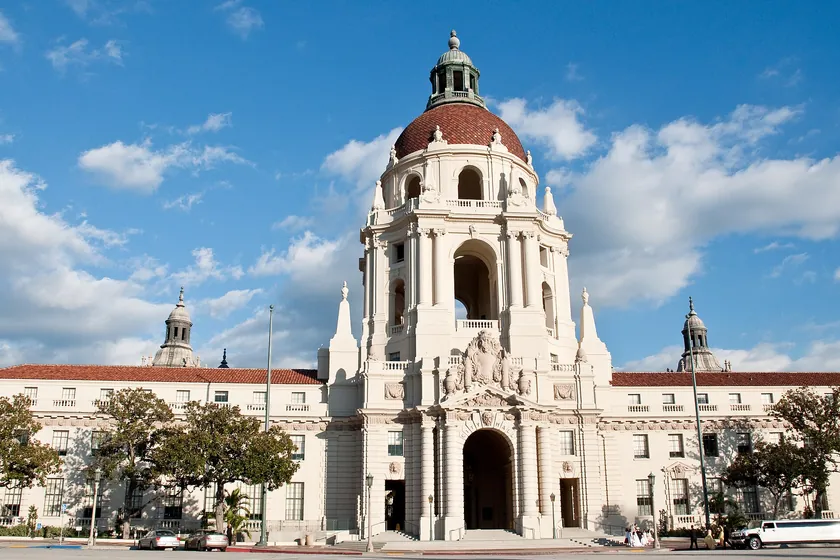
Pasadena sits almost exactly at the crossover point between the two halves of the reverse mortgage world. The citywide average value, about $1,186,000 by Zillow’s index, lands just under the 2026 FHA HECM limit of $1,249,125, which means many Pasadena homes still get full use of the federally insured program. Step up into Madison Heights, San Rafael, or the Linda Vista hills and values clear the limit, where proprietary jumbo programs to $4 million take over. Pasadena is the city where I most often run both calculations side by side, because the better answer genuinely changes house by house.
The character of the housing stock matters here in a way it doesn’t everywhere. Craftsman and Greene & Greene-era homes reward maintenance and punish deferral, and a growing line of credit is one of the most sensible ways I know for a long-tenure owner to fund a re-roof, a foundation bolt, or a kitchen that finally works, without a HELOC payment on a fixed income.
Pasadena also has a distinctly professional retiree base: Caltech, JPL, Huntington Hospital, the courts. These are clients who read the fine print, and I welcome that. Bring your financial advisor or your estate attorney into the conversation; the math either works or it doesn’t, and I’ll show it to you either way.
What a Pasadena file has that others don’t
Craftsman and Spanish stock from the teens and twenties is Pasadena’s signature and the appraiser’s homework: raised foundations, galvanized supply lines, the occasional knob-and-tube circuit in a back bedroom. None of it is automatically disqualifying. Condition findings become repair set-asides funded from the loan itself, and the right order is to tell me the house’s true state on the first call so the appraisal confirms a plan instead of writing one.
91103 produced the most insured loans in the past year, nine, with three capped, and 91104 added five more with three capped. When nearly half a city’s files hit the federal ceiling while the typical value sits under it, the lesson is that Pasadena’s averages hide a wide spread. The street decides the program more than the city does.
Landmark districts, Mills Act agreements, decades-old family trusts: Pasadena files arrive with paper. All of it coexists with a reverse mortgage; a Mills Act contract, for instance, keeps taxing the home at its favorable rate, and the loan simply requires that the (smaller) bill keep getting paid. The work is in reading the documents early, which I do before anyone orders an appraisal.
How each program fits Pasadena
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Pasadena home lands; your own age and value may point elsewhere.
What every Pasadena borrower must know
Who qualifies: homeowners 62 and over for the FHA HECM, 55 and over on most proprietary jumbo programs, occupying the Pasadena home as the primary residence, with meaningful equity and a financial assessment that shows the obligations below hold. Counseling with a HUD-approved agency precedes every HECM, chosen freely from the federal roster (national line: 800-569-4287); California’s cooling-off period follows before you are bound.
What remains yours: the county tax bill, and note that a Mills Act home’s reduced bill still must be paid in full; insurance; HOA dues where applicable; and the real upkeep an older home asks for. Keep those current and no monthly mortgage payment is required while you live there. Miss them and the loan can be called. For tight budgets, the tax-and-insurance set-aside is the tool, and on 1920s housing a repair set-aside often rides along.
What protects you: title remains with you or your trust, landmark status and all. Non-recourse means the obligation can never outgrow the home’s value at repayment, and whatever equity remains after payoff passes to you or your heirs.
Pasadena’s long-tenure owners often hold decades-old Proposition 13 assessments. A reverse mortgage does not reassess the property; the tax base stays where it is. For owners considering historic-property Mills Act contracts, those tax arrangements are likewise undisturbed; you simply remain responsible for paying whatever the tax bill is.
Pasadena questions, straight answers
My home is worth just over the HECM limit. Which program applies?
Both, and that’s the point: I run them side by side. The HECM uses the $1,249,125 limit in its calculation even if your home is worth more; a jumbo program uses your actual value. Depending on your age and rates, either one can win. Pasadena is exactly the market where comparing them matters most.
Can I use reverse mortgage proceeds to restore or repair my Craftsman?
Yes: proceeds are yours to use, and funding major maintenance on a historic home is one of the most common uses I see in Pasadena. A growing line of credit is often the right structure: draw for the roof this year, leave the rest growing for whatever comes next.
We're Caltech/JPL retirees with a good pension and investments. Why would we consider this?
For many of my Pasadena clients it isn’t about needing cash; it’s portfolio strategy. A standby HECM line of credit gives you a non-market source of funds to draw in down years instead of selling investments at a loss. The sequence-of-returns research on this is substantial; I’m happy to share it with you or your advisor.
Does the house have to leave our trust?
No. Reverse mortgages routinely close inside revocable living trusts, and with the estate-planning culture in Pasadena, most of my files here involve one. I coordinate directly with your estate attorney when needed.
Our Bungalow Heaven house is under a Mills Act contract. Does that complicate the loan?
Less than people fear. The contract lowers the tax bill; the loan requires the bill be paid, whatever its size, so the two coexist fine. The appraiser will note the landmark district, and preservation obligations stay yours as before. Bring the contract to the first call so nothing surprises escrow.
The sewer lateral and the roof both have maybe five years left. Fix before or after?
Usually after, from the loan. If the appraiser calls for repairs, a set-aside funds them right at closing; if the house passes as-is, the line of credit pays for the work on your schedule instead of your savings’. Paying cash for major repairs right before a reverse mortgage is the most common unforced error I see in this city.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
Pasadena owners usually ask these next; each question has its own page:
- What a reverse mortgage actually costs: the honest cost table and which lines the loan absorbs at closing.
- HECM line of credit compared with a bank HELOC: a comparison that matters where equity is large and incomes are fixed.
- The reverse mortgage glossary: every disclosure term, defined the way escrow actually uses it.
- Who qualifies for a reverse mortgage: the six requirements, older-home and condo footnotes included.
- How reverse mortgage rates work: expected rate, margin, and why two same-day quotes can differ.
- Helping a parent decide: for the children of the house, before the family meeting.
When the appraisal will clear the federal line, as it does above the Arroyo and in San Rafael, begin with jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Pasadena numbers.
Your Pasadena figures, both programs, in writing after one short call.
- A call back within minutes during California business hours
- The two-column quote with every cost shown
- An honest pass when the house or the plan says wait
Rather talk it through now?
Give me the street, the year the house was built, and what you want the equity to do. Pasadena rewards preparation: the files that close smoothly here are the ones where the title, the contract, and the condition were read before the calculator.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide