Reverse Mortgage Broker Serving Long Beach, California
Long Beach’s classic neighborhoods (Bixby Knolls, Belmont Heights, Los Altos, Naples) are full of homeowners who bought in the aerospace and port years and stayed. That patience built serious equity. Here’s how to use it with no required monthly mortgage payment, as long as you keep up the taxes, insurance and upkeep.
Forty-four insured loans, and arithmetic that leans FHA.
Because FHA records each reverse mortgage it insures, the local market is a matter of public record rather than guesswork. Here are the Los Angeles County and Long Beach lines for September 2025 through August 2026.
| HECMs insured by FHA, Los Angeles County | 818 |
| Of those, purchases (HECM for Purchase) | 14 |
| Reached the FHA ceiling | 21.0% |
| In Long Beach itself | 44 |
| Long Beach: reached the ceiling | 9.1% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
The county backdrop: 21% of Los Angeles County’s FHA endorsements in the past year reached the ceiling, 79% did not. That is a record of past loans, not a quota for yours, and it is why both programs get priced before I recommend one.
Long Beach supplied 44 of those loans, and only 9.1% reached the ceiling, less than half the county rate. On this side of the 405 the federal program usually gets to count the whole house.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Long Beach by ZIP code
All eleven Long Beach ZIP codes, from the 90802 downtown blocks to 90815, with the HECMs HUD recorded in each during the past year and the typical value against the federal limit.
Long Beach HECMs insured in the past year
Of the 11 Long Beach ZIP codes, 10 have a typical value under the $1,249,125 limit and 1 is over it; typical values run from about $476,000 to $1,331,000. The most loans were in 90808: 10 of the 44.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 90802 | 1 | 0 | $476,000 | Under |
| 90803 | 1 | 0 | $1,331,000 | Over |
| 90804 | 1 | 0 | $688,000 | Under |
| 90805 | 7 | 0 | $711,000 | Under |
| 90806 | 1 | 0 | $784,000 | Under |
| 90807 | 6 | 0 | $952,000 | Under |
| 90808 | 10 | 2 | $1,032,000 | Under |
| 90810 | 4 | 0 | $709,000 | Under |
| 90813 | 2 | 0 | $579,000 | Under |
| 90814 | 2 | 1 | $987,000 | Under |
| 90815 | 9 | 1 | $1,042,000 | Under |
All 44 HECMs HUD recorded with a Long Beach address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 40 FHA-approved condominium projects with a Long Beach mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Long Beach loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Long Beach bottom line: with the typical home near $852,000 against a 2026 HECM maximum claim amount of $1,249,125, this is one of the coast’s best-aligned FHA markets, and the record shows it: 44 loans insured in the past year, nine in ten under the ceiling. Belmont Shore, Naples, and owners aged 55 to 61 have the proprietary jumbo route to $4 million. Either way, living in the home with taxes, insurance, and maintenance current means no required monthly principal-and-interest payment.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The Long Beach picture
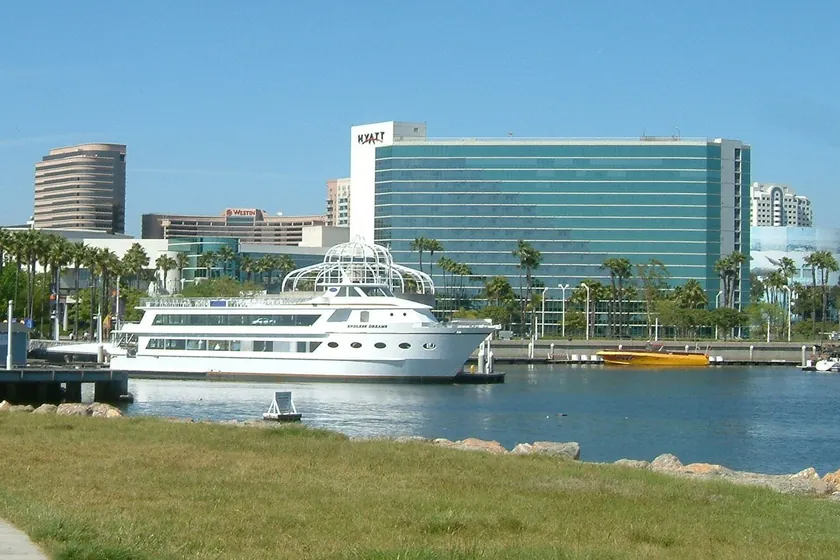
Long Beach is one of the best-fitting HECM markets in Southern California, and the reason is arithmetic. The citywide Zillow average sits near $852,000, comfortably under the 2026 FHA lending limit of $1,249,125. When the home’s value is below the limit, the federally insured HECM can work with the entire value of the home, which makes the program unusually efficient here compared with pricier coastal cities where the limit caps the calculation.
The housing stock tells the story: Spanish and Craftsman homes from the 1920s and 30s in Belmont Heights and California Heights, the postwar tracts of Los Altos and Plaza built for Douglas Aircraft families, the canal homes of Naples. Many owners are retirees of the port, the aerospace plants, the school district, or the city itself: steady pensions, long tenure, and a house that quietly became the largest asset they own.
A practical note for older Long Beach homes: a 90-year-old roof or foundation issue can surface in the appraisal. That is rarely a dead end; repairs can often be handled through a set-aside or completed before closing, but it is the kind of thing an experienced broker plans for on day one rather than discovers in week five.
Where Long Beach actually uses this loan
Ten of the 44 insured loans in the past year sat in 90808, the postwar grids of Los Altos and the Plaza where Douglas-era families bought in the fifties and never left. Typical value there is about $1,032,000, still under the limit, so the HECM counts effectively all of it. Two of the ten did reach the ceiling, a reminder that a typical value describes the middle of a street, not every house on it.
90803, from Belmont Heights through Naples, is the one Long Beach ZIP code whose typical value, about $1,331,000, clears the federal limit. HUD recorded a single insured loan there in the past year. Canal-front and Shore homes usually deserve the jumbo quote first, and the difference between the two columns on a $1.6 million house is large enough to be the whole decision.
A surprising share of Long Beach files start with a title chore: a late spouse still on the deed, a 1970s family trust nobody restated, a quitclaim from a divorce that never recorded. None of these are disqualifiers. They are sequencing. I read the title profile before quoting so escrow spends its days funding, not untangling.
How each program fits Long Beach
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Long Beach home lands; your own age and value may point elsewhere.
What every Long Beach borrower must know
Who qualifies: 62 and older for the FHA HECM; 55 to 61 belongs to the proprietary programs. The Long Beach home has to be the primary residence, with real equity and a financial assessment showing the obligations below are sustainable. HUD-approved counseling comes first, from any agency on the federal roster, your choice entirely (national line: 800-569-4287), and California layers a cooling-off period on top before anything binds.
What you keep paying: the full LA County tax bill including its assessments, insurance on the home, HOA dues if your building has them, and honest maintenance, salt air and all. Do that and no monthly mortgage payment is required while you live there; fall behind and the loan can become due and payable. Where the margin is thin, a tax-and-insurance set-aside inside the loan removes the risk, and I recommend one freely.
What protects you: you keep title, personally or in your trust. Non-recourse insurance means neither you nor your children can ever owe beyond the home’s value at payoff, and every remaining dollar of equity after a sale is the family’s.
Long-tenure Long Beach owners often carry a Proposition 13 assessment from the 1970s or 80s. A reverse mortgage leaves that tax base untouched. Owners 55+ who eventually sell can carry the low base to a replacement home anywhere in California under Proposition 19, useful if single-level living somewhere quieter is the long-range plan.
Long Beach questions, straight answers
Is my older Long Beach home a problem for the appraisal?
Age itself is not a problem; character homes appraise every day here. What matters is condition: roof, foundation, and health-and-safety items. If the appraiser calls something out, we can usually address it with a repair set-aside from the loan proceeds rather than losing the deal.
I have a pension from the port and Social Security. Do I have to income-qualify?
There is a financial assessment, but it is not like qualifying for a traditional mortgage. The lender reviews your history of paying property taxes and insurance and your residual income. Steady pension income like yours typically passes comfortably; when it’s tight, a set-aside for taxes and insurance can solve it.
How much of my home’s value can I actually get?
It depends on the youngest borrower’s age, current interest rates, and the home’s value; there is no flat percentage. Because Long Beach values generally sit under the FHA limit, the calculation uses your full appraised value, which works in your favor. I run the actual numbers for your address and age in a few minutes.
Can I use a reverse mortgage on my duplex in Rose Park?
Often yes. FHA allows HECMs on 2–4 unit properties when you live in one of the units as your primary residence. Long Beach has a lot of these. The rental income from the other unit keeps arriving, and the mortgage payment goes away.
Our place near the water in 90803 is worth about $1.6 million. What changes for us?
The FHA calculation stops counting at $1,249,125, so roughly $350,000 of your value would sit outside it. A proprietary jumbo counts the full figure, prices differently, and skips the FHA insurance premium. Sometimes the HECM’s growing credit line still wins anyway. That is a two-column quote, in writing, before you choose.
My late husband is still on the deed. How big a problem is that?
A solvable one, and common. Title gets cleared through an affidavit of death or a trust administration step depending on how you held the property, usually in days to a few weeks. We order that work at the start so it runs parallel to the appraisal instead of after it. Bring whatever recorded documents you have to the first call.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The questions Long Beach files generate next, each with a page of its own:
- What a reverse mortgage actually costs: six cost categories in dollars and which ones ride inside the loan.
- HECM line of credit compared with a bank HELOC: why retirees keep the line a bank can freeze and seniors keep the one that grows.
- The reverse mortgage glossary: forty-eight defined terms for reading your disclosures without a translator.
- Who qualifies for a reverse mortgage: all six requirements, with the duplex and condo wrinkles spelled out.
- How reverse mortgage rates work: what the margin does to proceeds and how two quotes get compared fairly.
- Helping a parent decide: the adult-child briefing: house, inheritance, and the questions worth asking.
If the appraisal will land past the federal line, as it can from Belmont Heights to Naples, start with jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Long Beach numbers.
Fifteen minutes gets your Long Beach figures on paper: proceeds, costs, and what doing nothing looks like.
- A call back within minutes during California business hours
- Both program columns, written, before any commitment
- A plain no whenever the numbers say no
Rather talk it through now?
Bring me the address and the goal, a paid-off Plaza house, a Bixby Knolls trust, a balance that needs to go away, and you will get the honest arithmetic. Forty-four Long Beach families ran it in the past year; most found the FHA column already fit.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide