Reverse Mortgage Broker Serving San Diego, California
San Diego rewarded the people who stayed — the Navy families in Clairemont, the engineers in Rancho Bernardo, the teachers in Allied Gardens. Their homes now hold the retirement fund nobody set out to build.
A hundred sixty-seven files, Clairemont to the coast.
Because HUD publishes its endorsement file monthly, loan by loan, the San Diego market can be counted instead of guessed at. County and city, September 2025 through August 2026:
| HECMs insured by FHA, San Diego County | 478 |
| Of those, purchases (HECM for Purchase) | 12 |
| Reached the FHA ceiling | 20.5% |
| In San Diego itself | 167 |
| San Diego: reached the ceiling | 19.2% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
San Diego County’s share of past-year endorsements at the FHA ceiling: 20%, with 80% underneath it. Those are recorded loans, not predictions; their one instruction is that a serious quote here prices the federal and proprietary programs together.
The city produced 167 of those insured loans, 19.2% capped, nearly the county rate exactly. With 33 ZIP codes in play, the useful question is never the citywide percentage; it is which San Diego your house is in.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
San Diego by ZIP code
One citywide number hides a city where typical values run from about $581,000 to about $2.9 million. Here is the same federal loan record, broken down by ZIP code, beside Zillow’s typical home value for each one.
San Diego HECMs insured in the past year
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 92117 | 17 | 5 | $1,074,000 | Under |
| 92114 | 13 | 0 | $737,000 | Under |
| 92120 | 13 | 3 | $1,021,000 | Under |
| 92126 | 11 | 0 | $980,000 | Under |
| 92111 | 10 | 1 | $934,000 | Under |
| 92115 | 10 | 0 | $844,000 | Under |
| 92119 | 9 | 0 | $968,000 | Under |
| 92110 | 8 | 3 | $980,000 | Under |
| 92128 | 8 | 1 | $986,000 | Under |
| 92154 | 8 | 0 | $746,000 | Under |
| 92123 | 7 | 0 | $944,000 | Under |
| 92116 | 6 | 1 | $985,000 | Under |
| 92102 | 5 | 1 | $743,000 | Under |
| 92104 | 5 | 1 | $939,000 | Under |
| 92108 | 5 | 0 | $581,000 | Under |
The 15 ZIP codes with five or more loans: 135 of the 167 HECMs HUD recorded with a San Diego address. The other 32 were spread across 12 more ZIP codes. The limit is the 2026 HECM maximum claim amount of $1,249,125.
The busiest ZIP code, 92117, had 17 loans. Its typical value, about $1,074,000, is under the limit, yet 5 of the 17 reached the ceiling, because a typical value is the middle of the market, not every house. In 92114, 92126 and 92115, where typical values run from about $737,000 to $980,000, 34 loans were insured and none reached the ceiling. The coast is a different market: typical values of about $2.3 million in 92037, $1.8 million in 92106, and $1.5 million in 92107 and 92109. Only 3 of the city’s 167 loans were in those four ZIP codes, and 2 of the 3 reached the ceiling.
Find your ZIP code: all 33 San Diego ZIP codes against the HECM limit
24 of the 33 ZIP codes Zillow assigns to the City of San Diego have a typical value under the $1,249,125 limit; 9 are above it.
- 92014$2,879,000Over
- 92037$2,349,000Over
- 92101$708,000Under
- 92102$743,000Under
- 92103$1,063,000Under
- 92104$939,000Under
- 92105$683,000Under
- 92106$1,807,000Over
- 92107$1,510,000Over
- 92108$581,000Under
- 92109$1,481,000Over
- 92110$980,000Under
- 92111$934,000Under
- 92113$645,000Under
- 92114$737,000Under
- 92115$844,000Under
- 92116$985,000Under
- 92117$1,074,000Under
- 92119$968,000Under
- 92120$1,021,000Under
- 92121$1,051,000Under
- 92122$1,056,000Under
- 92123$944,000Under
- 92124$1,043,000Under
- 92126$980,000Under
- 92127$1,593,000Over
- 92128$986,000Under
- 92129$1,322,000Over
- 92130$2,068,000Over
- 92131$1,452,000Over
- 92139$732,000Under
- 92154$746,000Under
- 92173$682,000Under
All 478 HECMs in San Diego County carried an adjustable rate, including all 167 with a San Diego address. Nationally it was 24,517 of 24,529. The reason is structural: a fixed-rate HECM is one lump sum at closing, limited by HUD’s first-year rules, with no line of credit afterward. Anyone who wants a line of credit or monthly payments takes the adjustable version.
For the typical San Diego borrower, the principal limit (the most the loan makes available) was 46.4% of the value HUD counted: the appraised value, or the FHA limit when the home is worth more. Countywide it was 45.5%. Age decides most of the difference from one borrower to the next: the older the youngest borrower, the higher the share.
HUD’s list shows 184 FHA-approved condominium projects with a San Diego mailing address (searched October 16, 2026). If your address uses a community name, such as La Jolla, search under that name. A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each San Diego loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The San Diego answer: with the citywide average near $980,000 against the 2026 HECM maximum claim amount of $1,249,125, most of the city remains full-value FHA territory for owners 62 and older, and the records back it up, 167 insured loans in the past year, four of five under the ceiling. La Jolla, Point Loma, the coast generally, and owners aged 55 to 61 belong with the proprietary jumbo programs on values to $4 million. Both routes require no monthly principal-and-interest payment while you live in the home and keep taxes, insurance, and maintenance current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Typical value: Zillow Home Value Index, data through September 30, 2026, rounded.
The San Diego picture
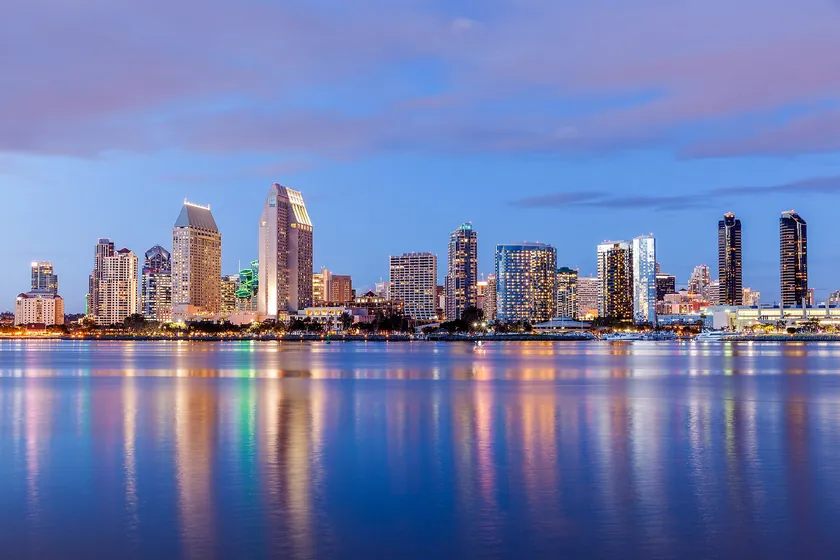
San Diego sits at the fulcrum: Zillow’s citywide average of about $980,000 lands under the 2026 FHA HECM limit of $1,249,125, keeping the mid-century neighborhoods (Clairemont, Serra Mesa, Allied Gardens, much of Rancho Bernardo) in full-value HECM territory, while Point Loma, La Jolla, and the coastal strip run past the limit into jumbo range, where proprietary programs lend to $4 million from age 55. Few cities require the two-program comparison as routinely as this one.
San Diego is also a military town, and I’ll say the important thing directly: there is no VA reverse mortgage. Veterans and military retirees use the same HECM and jumbo programs as everyone else, and with the pension and healthcare picture many retirees here already have, the reverse mortgage’s job is usually precise: eliminate a remaining payment, or build a standby line for the later-care years. Anyone marketing a “veteran’s reverse program” deserves your skepticism.
The county’s 55+ landscape matters too: from Rancho Bernardo’s Seven Oaks and Oaks North to the broader right-sizing migration toward single-level living. HECM for Purchase carries real weight here: it lets the move happen with roughly 55 to 70 percent down (depending on age, plus closing costs) and no required monthly principal and interest payment, keeping the rest of the sale proceeds liquid for the years ahead.
What 167 San Diego files say
92117 wrote 17 insured loans in the past year, more than any other San Diego ZIP code: canyon-rim mid-centuries held for forty years by owners who are not moving. Five of the seventeen still reached the ceiling on a typical value of about $1,074,000, proof that a typical value is the street’s midpoint, not its boundary, and a reason quotes here come in two columns even east of the 5.
San Diego files regularly arrive with a pension, VA disability income, and Tricare in place of employer benefits. All of it counts cleanly in the financial assessment, and the loan’s job is usually precision: erase a remaining balance in Tierrasanta or 92120, add a growing line for the years after the surviving-spouse math changes. Bring the award letters; they do real work.
In 92114, 92126, and 92115, Encanto to Mira Mesa to the College Area, 34 loans were insured in the past year and not one reached the ceiling, on typical values from about $737,000 to $980,000. That is the federal program operating exactly as designed: whole-house calculations for long-tenured owners on ordinary streets, no ceiling anywhere in sight.
How each program fits San Diego
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical San Diego home lands; your own age and value may point elsewhere.
What every San Diego borrower must know
Who qualifies: the FHA HECM at 62 and up; proprietary jumbo from 55 for the coast and the under-62. The home, house or approved condo, must be your primary residence with meaningful equity, and the financial assessment must show capacity for the obligations below. Counseling through a HUD-approved agency you select from the federal roster precedes every HECM (national line: 800-569-4287), with California’s cooling-off period layered on.
Continuing obligations: the San Diego County tax bill entire, homeowner’s insurance, HOA dues for the condo files this city runs in volume, and true upkeep. Current, and no monthly mortgage payment is required while the home is yours to live in; delinquent, and the loan can be called due. Where income is pension-steady but tight, the tax-and-insurance set-aside turns the risk into a non-event.
What protects you: title stays with you or your trust. The non-recourse guarantee caps any repayment at the home’s value, period, and equity beyond the balance passes to you or your heirs at sale, every dollar.
Long-tenure San Diego owners hold Prop 13 assessments that a reverse mortgage will not disturb: no reassessment, no title change. Proposition 19 adds the mobility piece: owners 55+ can transfer the low base to a replacement home anywhere in California, up to three times, which pairs naturally with a HECM for Purchase move to single-level living in Rancho Bernardo or beyond.
San Diego questions, straight answers
Is there a VA reverse mortgage for veterans?
No: the VA does not offer one, and marketing that implies otherwise is a red flag. Veterans use the standard FHA HECM or proprietary jumbo programs. VA disability compensation and military retired pay aren’t means-tested, so loan advances don’t affect them. A needs-based VA pension, including Aid and Attendance, is different: money drawn and kept can count toward its net-worth limit, so draw only what you’ll spend and check with a VA-accredited advisor first.
Our Clairemont home is worth about $950,000. Which program fits?
That's clean HECM territory: under the federal limit, so the calculation uses your full value, and the HECM’s growing line of credit and tenure-payment options are all on the table. I’ll still show you the jumbo comparison, but at that value the HECM usually carries the day.
We want to move from our two-story to a single-level in Rancho Bernardo. How?
HECM for Purchase: sell the two-story, put roughly 55 to 70 percent of the new price down from proceeds, depending on age, finance the balance with no required monthly principal-and-interest payment, and keep the remaining cash liquid. In the 55+ communities, I also verify FHA condo approval where applicable before you write an offer.
How does the required counseling work in San Diego?
Before any HECM application, you complete an independent session with a HUD-approved counseling agency, by phone or in person, about an hour, typically about $125–$200. You choose the agency freely from the HUD roster (I’m required to give you a list and prohibited from steering you). HUD’s national line is (800) 569-4287.
Our Rancho Bernardo association just passed a special assessment. Does that sink the file?
No, it joins the arithmetic. One-time assessments can often be paid from proceeds at closing; ongoing increases fold into the budget review beside dues and taxes. What actually sinks condo files is association eligibility, so I check the project’s status the same week we talk, before anyone spends money on an appraisal.
We rent out the ADU in the backyard. Help or hurt?
Usually help. A permitted ADU typically appraises with the property, and its rent can support the financial assessment. The property still must be your primary residence, and permits matter, unpermitted conversions get valued cautiously. Bring the rental figures and permit history to the first call and I will tell you how the appraiser is likely to read it.

Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The next questions on most San Diego files, each with its own page:
- What a reverse mortgage actually costs: all the costs in dollars, with the financed-versus-cash split shown.
- HECM line of credit compared with a bank HELOC: which line serves a pension-based budget, and why.
- The reverse mortgage glossary: the full disclosure vocabulary, principal limit to set-aside.
- Who qualifies for a reverse mortgage: six requirements, with the condo-approval path explained.
- How reverse mortgage rates work: index, margin, expected rate, and reading a quote like a broker.
- Helping a parent decide: for the kids in Poway or across the country, before the decision.
Coastal and La Jolla values the federal calculation cannot fully count are the business of jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your San Diego numbers.
One call returns your San Diego figures in writing, pension and VA income handled correctly, both programs priced.
- A call back within minutes during California business hours
- Condo association eligibility checked before you spend a dollar
- An honest pass when doing nothing wins
Rather talk it through now?
Tell me the neighborhood, the ages, and the mission, payoff, monthly cushion, or a move to single-level, and the answer comes back in columns, not slogans. A hundred sixty-seven San Diego families ran this math in the past year; yours deserves the same precision.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide