Reverse Mortgage Broker Serving Oceanside, California
FHA insured 42 reverse mortgages in Oceanside in the past year, the second most in San Diego County. Most Oceanside homes fit the FHA program; the coastal strip is where the two calculations start to compete.
Run both calculations here. Neither one is obvious.
Every FHA-insured reverse mortgage is logged by HUD as it is endorsed. These are the San Diego County figures and Oceanside’s own, drawn from the twelve monthly releases between September 2025 and August 2026.
| HECMs insured by FHA, San Diego County | 478 |
| Of those, purchases (HECM for Purchase) | 12 |
| Reached the FHA ceiling | 20.5% |
| In Oceanside itself | 42 |
| Oceanside: reached the ceiling | 11.9% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
About 20% of federally insured reverse mortgages in this county hit the FHA ceiling, which means roughly 80% did not. That split is exactly why I run the HECM and the jumbo side by side rather than leading with one.
In Oceanside specifically, 42 of those loans were on homes inside the city limits, and 11.9% of them reached the ceiling.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Oceanside by ZIP code
The four Oceanside ZIP codes Zillow tracks, each with its HECM count from HUD over the past year and its typical value against the 2026 FHA limit.
Oceanside HECMs insured in the past year
All 4 Oceanside ZIP codes have a typical value under the $1,249,125 limit, from about $787,000 to $1,117,000. The most loans were in 92057: 19 of the 42.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 92054 | 4 | 2 | $1,117,000 | Under |
| 92056 | 17 | 0 | $860,000 | Under |
| 92057 | 19 | 3 | $805,000 | Under |
| 92058 | 2 | 0 | $787,000 | Under |
All 42 HECMs HUD recorded with an Oceanside address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 17 FHA-approved condominium projects with an Oceanside mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Oceanside loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Oceanside bottom line: 42 insured reverse mortgages in the past year, the second most of any San Diego County city, with 37 under the FHA ceiling. Inland Oceanside is squarely HECM territory; the coastal strip and the top of the market are where the proprietary jumbo, on values to $4 million and from age 55, earns the comparison. In either program, no monthly principal-and-interest payment is required while you live in the home and keep taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Loan counts: HUD FHA HECM Single-Family Portfolio Snapshot, September 2025 through August 2026.
The Oceanside picture
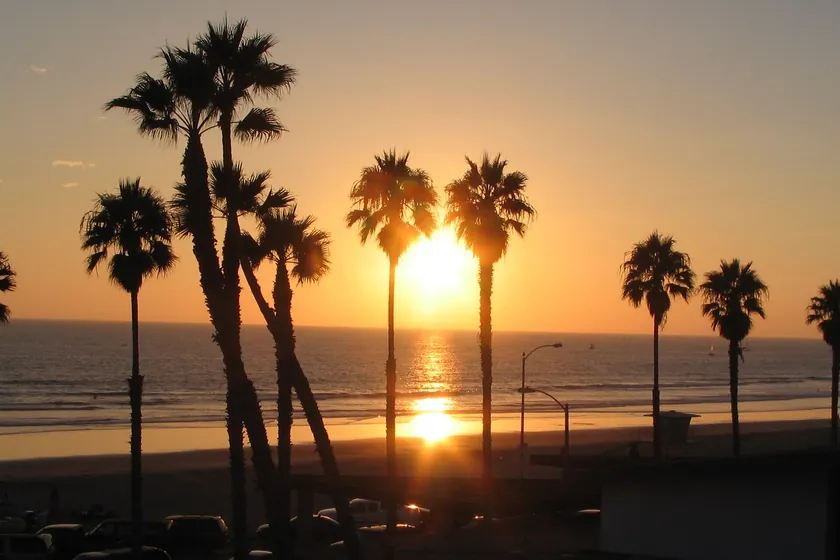
Oceanside is really three markets. The coastal neighborhoods west of the freeway carry some of the highest values in the city. Inland, Rancho del Oro, Fire Mountain and the neighborhoods along the 76 corridor are mid-century and later tract homes owned by the same families for decades. And Ocean Hills Country Club is one of North County’s best-known age-restricted communities, full of owners for whom a reverse mortgage is a very ordinary conversation.
HUD’s records show the split: 11.9% of Oceanside’s HECMs reached the FHA ceiling, well below the county’s 20.5%. So for most Oceanside homes the HECM counts essentially the full value, and it is the program to start with. For the coastal homes above the limit, I run the proprietary jumbo beside it and let the numbers decide.
Camp Pendleton’s long presence means a lot of military retirees here, and two questions come up constantly. VA disability compensation is not means-tested, so reverse mortgage proceeds do not affect it. A needs-based VA pension is different: loan proceeds are not income, but money you draw and hold into the next month can count as an asset. The rule is the same one I give Medi-Cal households: draw what you spend.
How Oceanside files actually run
Oceanside’s busiest reverse mortgage ZIP in the past year was 92057, with 19 of the city’s 42, and a healthy share of those sit in established 55-plus and planned communities like Ocean Hills Country Club. The mechanics are routine: association dues join taxes and insurance on the must-stay-current list, the financial assessment counts them, and for condominium forms of ownership I confirm FHA approval before quoting a number rather than after.
This is a Camp Pendleton town, and many Oceanside files involve military retirement pay or VA disability compensation. Those are not means-tested, and reverse mortgage proceeds are loan advances rather than income, so they do not touch them. The caution sits with needs-based programs such as SSI or Medi-Cal, where money kept in the bank past month-end can count against limits. That is a planning detail, not a dead end, and it gets handled on the first call.
West of the 5, values climb toward and past the point where the FHA calculation stops counting, and five Oceanside loans in the past year did reach the federal ceiling. For those addresses I run the HECM and the jumbo side by side on one page: sometimes the insured program still wins on cost and its growing line of credit, sometimes the jumbo frees meaningfully more of the house. The address decides, not a slogan.
How each program fits Oceanside
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Oceanside home lands; your own age and value may point elsewhere.
What every Oceanside borrower must know
Who qualifies: age 62 and up for the FHA HECM, 55 and up on many jumbo programs, in a home that is your primary residence, with sufficient equity and a financial assessment showing the obligations below are sustainable. Every HECM starts with independent counseling from a HUD-approved agency that you select yourself from the federal roster (national line: 800-569-4287); California’s own cooling-off period runs on top of the federal rules before anything binds.
What never leaves your side of the table: the property tax bill in full, homeowner’s insurance, association dues in Oceanside’s many planned and 55-plus communities, space rent where that applies, and ordinary maintenance. Current on those, you owe no monthly mortgage payment while the home is your residence; behind on them, the loan can become due and payable. When automation is the safer plan, a tax-and-insurance set-aside inside the loan handles it.
What protects you: title stays with you or your trust. Non-recourse means the payoff can never exceed the home’s value at the time it is repaid, whatever the market has done, and any equity above the payoff when the home sells belongs to you or your heirs outright.
Oceanside has many manufactured-home communities, and eligibility turns on the land. A HECM requires a manufactured home built after June 15, 1976, on a permanent foundation, titled as real property, on land you own. A home in a park where you rent the space does not qualify, however long you have lived there. Ask me before you assume either way; it is a two-minute question.
Oceanside questions, straight answers
We live in Ocean Hills Country Club. Anything special about a reverse mortgage there?
Single-family homes in an age-restricted community are routinely eligible. The HOA dues become part of your ongoing obligations alongside property taxes and insurance, and the lender will want the association’s information. Nothing about the 55+ restriction itself is an obstacle.
I receive VA disability compensation. Will a reverse mortgage affect it?
No. VA disability compensation is not needs-based, so loan proceeds do not reduce it. A needs-based VA pension is different: proceeds are not income, but funds kept past the month you receive them can count as assets. Draw what you need rather than taking a large lump sum you will hold.
Is my coastal home too valuable for the FHA program?
It may be above the $1,249,125 limit the HECM will count. That does not make it ineligible; the calculation simply stops at the limit. Above it, a proprietary jumbo calculates on the full appraised value, and I run both side by side.
Our home is in a mobile home park. Can we get a reverse mortgage?
Not if you rent the space. A HECM requires that you own the land and that the home is titled as real property, built after June 15, 1976, on a permanent foundation. If you own your lot, it is worth a call.
We are in a 55+ community with dues and a land lease. Which parts matter?
All of it, in different ways. Association dues are an ongoing obligation the financial assessment counts. Owning the land under the home is what HECM eligibility turns on: owned land with a qualifying home works, rented space does not. Bring the exact community name and the title details to the first call and the answer takes ten minutes.
Could we sell inland and use a reverse mortgage to buy closer to the beach?
That is HECM for Purchase, and it works in Oceanside: roughly 55 to 70 percent down depending on age, no required monthly payment on the rest, and your remaining proceeds stay liquid. Near the coast the purchase price may push past the FHA limit, in which case the jumbo purchase programs take over. I price both before you write any offer.
Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The pages Oceanside callers end up reading next:
- What a reverse mortgage actually costs: the full cost anatomy, what is financed at closing, and the “no cost” decoder.
- HECM line of credit compared with a bank HELOC: which line survives retirement: payments, freezes, and staying power compared.
- The reverse mortgage glossary: forty-eight terms from the disclosures, translated into plain English.
- Who qualifies for a reverse mortgage: all six requirements, including the manufactured-home and condo rules.
- How reverse mortgage rates work: what sets the expected rate and how it moves what you can draw.
- Helping a parent decide: for sons and daughters weighing in: the house, the benefits, the real questions.
For the coastal strip and anything above the federal line, start at jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Oceanside numbers.
Fifteen minutes, one page: your Oceanside numbers with HECM and jumbo side by side, benefits questions answered.
- A call back within minutes during California business hours
- Figures in writing before anyone talks commitment
- A straight no whenever the math says no
Rather talk it through now?
Give me the address, the ages, and what you want the equity to do, and you get a direct answer, including on the benefits and land-lease questions that make Oceanside files particular. If the right move is nothing, that is what I will say.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide