Reverse Mortgage Broker Serving Carlsbad, California
More than half of Carlsbad’s federally insured reverse mortgages in the past year hit the FHA limit. In Carlsbad the proprietary jumbo calculation should usually be run first.
Run both calculations here. Neither one is obvious.
HUD records each FHA-insured reverse mortgage as it is endorsed, which makes the local pattern visible. Here are San Diego County and Carlsbad across the twelve monthly releases, September 2025 through August 2026.
| HECMs insured by FHA, San Diego County | 478 |
| Of those, purchases (HECM for Purchase) | 12 |
| Reached the FHA ceiling | 20.5% |
| In Carlsbad itself | 26 |
| Carlsbad: reached the ceiling | 53.8% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
About 20% of federally insured reverse mortgages in this county hit the FHA ceiling, which means roughly 80% did not. That split is exactly why I run the HECM and the jumbo side by side rather than leading with one.
In Carlsbad specifically, 26 of those loans were on homes inside the city limits, and 53.8% of them reached the ceiling.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Carlsbad by ZIP code
Zillow’s four Carlsbad ZIP codes, each with its HECM count from the past year and a typical value that, uniquely on this site, sits above the 2026 FHA limit in all four.
Carlsbad HECMs insured in the past year
All 4 Carlsbad ZIP codes have a typical value over the $1,249,125 limit, from about $1,277,000 to $1.7 million. The most loans were in 92009: 9 of the 26. Of the 26 loans, 14 reached the FHA ceiling, so the jumbo comparison matters here.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 92008 | 6 | 5 | $1,730,000 | Over |
| 92009 | 9 | 4 | $1,562,000 | Over |
| 92010 | 4 | 1 | $1,277,000 | Over |
| 92011 | 7 | 4 | $1,588,000 | Over |
All 26 HECMs HUD recorded with a Carlsbad address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 24 FHA-approved condominium projects with a Carlsbad mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Carlsbad loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Carlsbad bottom line: this is the one city on this site where the jumbo calculation comes first. Every Carlsbad ZIP carries a typical value above the $1,249,125 federal limit, and 14 of the 26 HECMs insured here in the past year reached the ceiling, meaning the FHA math counted less than the house. The proprietary jumbo counts appraised value to $4 million and starts at age 55; the HECM still earns its keep near the limit and through its growing line of credit. Both require no monthly principal-and-interest payment while you live in the home with taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Loan counts: HUD FHA HECM Single-Family Portfolio Snapshot, September 2025 through August 2026.
The Carlsbad picture
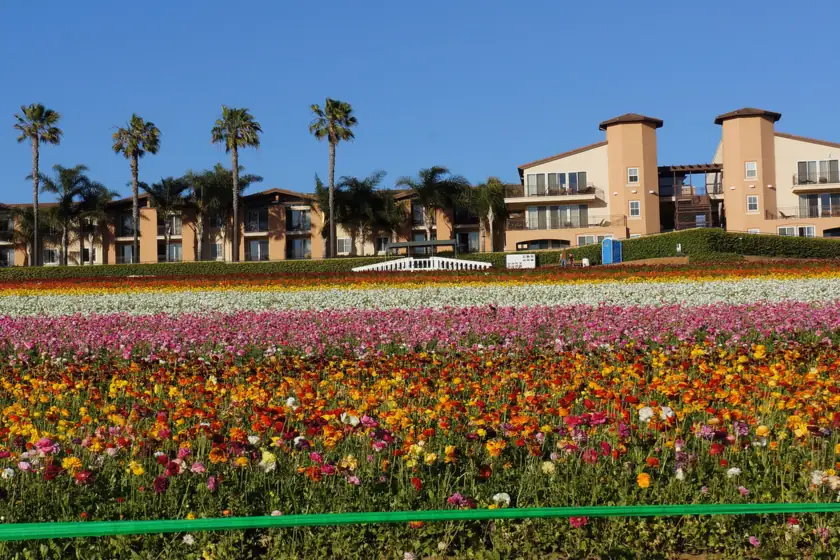
Carlsbad runs from the older cottages and beach streets of the Village to the golf-course neighborhoods of La Costa, the planned communities of Aviara and Calavera Hills, and the newer developments inland. Nearly everywhere, values have risen far enough that the FHA program cannot count the whole house.
HUD’s records make the point: of the 26 HECMs insured in Carlsbad in the past year, 53.8% reached the FHA ceiling of $1,249,125, more than double San Diego County’s 20.5%. For those homes, a proprietary jumbo reverse mortgage that counts the full appraised value, up to $4 million, will often produce considerably more. I still run the HECM beside it, because its growing line of credit and FHA-backed protections can outweigh a larger initial number for some households.
Two practical points come up here. Many Carlsbad communities carry HOA dues, and some carry Mello-Roos or other special assessments; both belong in the ongoing budget. And condominium units need FHA approval for a HECM, while jumbo programs apply their own condo standards, which can be more flexible.
Carlsbad files start from a different premise
When a La Costa or Aviara home appraises at $1.7 million, the HECM counts $1,249,125 of it and the jumbo counts all of it. That single difference decides most Carlsbad files, and it is why more than half the city’s insured loans in the past year sat at the federal ceiling. I still show both columns on one page, because the insured program’s costs and credit-line growth sometimes claw the decision back, but the starting point here is honest: count the whole house first.
Carlsbad’s busiest reverse ZIP in the past year was 92009, with 9 of the 26 loans. The pattern is long ownership south of the lagoon, a home that quietly became a seven-figure asset, and owners who want retirement funded without selling it. At these values the monthly arithmetic moves real money, so the one-page comparison is not a formality; it is the decision.
The jumbo programs’ age-55 start matters more in Carlsbad than almost anywhere inland, because the values support it. A 57-year-old here is not waiting five years for eligibility; the waiting question is strategic, since proceeds grow with age. I run the now-versus-at-62 comparison in writing, and either answer can win depending on the plan for the money.
How each program fits Carlsbad
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Carlsbad home lands; your own age and value may point elsewhere.
What every Carlsbad borrower must know
Who qualifies: 62 and older for the FHA HECM, and in Carlsbad the equally relevant line is 55 and older for several proprietary jumbo programs. The home must be your primary residence, the equity real, and the financial assessment satisfied on the obligations below. A HECM additionally requires independent counseling first, with a HUD-approved agency you select from the federal roster (national line: 800-569-4287), and California’s cooling-off period applies before anything is final.
What continues at Carlsbad scale: property taxes that are substantial at these values, homeowner’s insurance, HOA and master-association dues where they apply, and the maintenance a coastal home actually needs. Keep them current and no monthly mortgage payment is required while you live there; fail them and the loan can be called due and payable. Set-asides for taxes and insurance exist on jumbo files too, and I use them where they make the plan safer.
What protects you: title stays with you or your trust, in either program. The reputable jumbo programs I broker are non-recourse like the HECM: the payoff can never exceed the home’s value at repayment, and every remaining dollar of equity at sale belongs to you or your heirs.
Owners 55 and older who sell a Carlsbad home and buy another anywhere in California can carry their tax base under Proposition 19. If the replacement costs more, the difference is added to the transferred base. Because Carlsbad values are high, that transfer can be worth a great deal each year; I flag the claim deadline in every purchase file.
Carlsbad questions, straight answers
Our home is worth about $2 million. Which program makes sense?
Start with the jumbo. The HECM will count only $1,249,125 of the value in 2026. A proprietary program counts the full appraised value up to $4 million, with no FHA mortgage insurance premium. I run the HECM beside it so you can see what its line of credit growth is worth against the larger initial figure.
We are 57. Is a reverse mortgage possible?
Yes, through a proprietary program; the FHA HECM requires the youngest borrower to be 62. Proceeds at 57 are materially lower than the same home would support later, and I will show you that honestly.
Is a jumbo reverse mortgage still non-recourse?
Yes. On a HECM the protection comes from FHA insurance; on a jumbo it is written into the loan documents. Either way, neither you nor your heirs can owe more than the home is worth at repayment.
What must we keep paying after closing?
Property taxes including any assessments, homeowner’s insurance, HOA dues, and normal upkeep.
At $1.7 million in La Costa, roughly what does the jumbo free up that the HECM cannot?
The jumbo calculates on the full $1.7 million while the HECM stops at $1,249,125, so the jumbo’s base is about $450,000 larger before age and rate factors apply. What that converts to in proceeds depends on the youngest borrower’s age and pricing that week, which is why the answer you should act on is the written one, not a rule of thumb.
Does a jumbo reverse mortgage put our trust and estate plan at risk?
No more than any mortgage. Title can stay in a properly drafted living trust, subject to lender review, heirs inherit the home with a loan to settle, and non-recourse protection caps that payoff at the home’s value. At Carlsbad values I recommend your estate attorney see the structure before closing, and I work alongside them routinely.
Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The follow-up reading that fits Carlsbad files:
- Jumbo reverse mortgages for California homes: the program Carlsbad usually starts with: ages 55+, values to $4 million, structure and trade-offs.
- What a reverse mortgage actually costs: cost anatomy for both programs, and where jumbo pricing differs.
- HECM line of credit compared with a bank HELOC: why the growing line still argues for the insured program near the limit.
- The reverse mortgage glossary: the vocabulary of both disclosure stacks, defined plainly.
- How reverse mortgage rates work: expected rate, margin, and what moves proceeds at seven figures.
- How planners use reverse mortgages: the strategy layer: sequence risk, standby credit, and coordinated draws.
And for the minority of Carlsbad homes near or under the limit, the standard California HECM overview is the right first page.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Carlsbad numbers.
Fifteen minutes and your Carlsbad comparison is on one page: full-value jumbo beside the federal program, your ages, your home.
- A call back within minutes during California business hours
- The two-column page in writing before any decision
- If neither column justifies itself, I say so
Rather talk it through now?
Bring the value, the ages, and what the money is meant to do. At Carlsbad prices the difference between the two programs is real money, and seeing both columns on one page is what the first call is for.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide