Reverse Mortgage Broker Serving Modesto, California
None of Stanislaus County’s 60 federally insured reverse mortgages reached the FHA limit in the past year. In Modesto the HECM counts the whole house, and the question is how to use it.
Stanislaus County: sixty insured loans, zero at the limit.
Every FHA-insured reverse mortgage lands in HUD’s public records as it is endorsed. These are the Stanislaus County and Modesto lines from the twelve monthly releases, September 2025 through August 2026, and they say the program works well here, without an exception to speak of.
| HECMs insured by FHA, Stanislaus County | 60 |
| Of those, purchases (HECM for Purchase) | 4 |
| Reached the FHA ceiling | 0.0% |
| In Modesto itself | 29 |
| Modesto: reached the ceiling | 0.0% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Not one federally insured reverse mortgage in this county reached the FHA ceiling (0.0%). For almost everyone in this market the HECM calculation reaches essentially the full value of the home, and a proprietary jumbo would buy you nothing but a different cost structure. If you have been told otherwise, ask why.
In Modesto specifically, 29 of those loans were on homes inside the city limits, and 0.0% of them reached the ceiling.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Modesto by ZIP code
Seven Modesto ZIP codes, as Zillow tracks them, each with the HECMs HUD recorded in the past year and the typical value measured against the 2026 FHA limit.
Modesto HECMs insured in the past year
All 7 Modesto ZIP codes have a typical value under the $1,249,125 limit, from about $374,000 to $516,000. The most loans were in 95350: 7 of the 29. None of the 29 reached the FHA ceiling.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 95350 | 7 | 0 | $421,000 | Under |
| 95351 | 5 | 0 | $374,000 | Under |
| 95354 | 5 | 0 | $393,000 | Under |
| 95355 | 6 | 0 | $485,000 | Under |
| 95356 | 3 | 0 | $516,000 | Under |
| 95357 | 1 | 0 | $501,000 | Under |
| 95358 | 2 | 0 | $427,000 | Under |
All 29 HECMs HUD recorded with a Modesto address. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 2 FHA-approved condominium projects with a Modesto mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Modesto loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Modesto bottom line: not one of the 29 HECMs insured in Modesto in the past year reached the FHA ceiling, and with ZIP-level values running roughly $374,000 to $516,000, none came close. For homeowners 62 and older the federal calculation counts the whole house on every street in town; the proprietary jumbo programs, to $4 million, matter here mainly as the age-55-to-61 route. Whichever applies, living in the home with taxes, insurance, and upkeep current means no monthly principal-and-interest payment is required.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Loan counts: HUD FHA HECM Single-Family Portfolio Snapshot, September 2025 through August 2026.
The Modesto picture
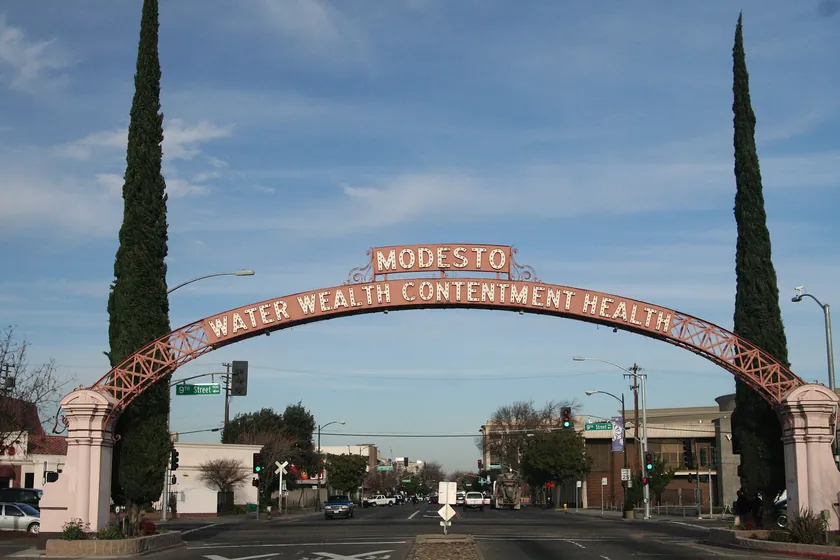
Modesto is an agricultural city with deep roots: tree-lined older neighborhoods near downtown and the College Area, postwar ranch homes across the middle of town, and newer subdivisions to the north. It has also drawn Bay Area buyers over the Altamont for decades, and many of them are now the ones calling about retirement.
HUD’s records make the program choice clear. Stanislaus County recorded 60 HECMs in the past year, 29 of them in Modesto, and not one reached the FHA ceiling. The federally insured program counts essentially every Modesto home at full value, with the features only it guarantees: a growing line of credit, tenure payments for life in the home, and FHA-backed non-recourse protection.
What I spend time on in Modesto files is the budget after closing. HUD’s financial assessment looks at whether taxes, insurance and upkeep can be carried on your income. Where it is close, a set-aside that pays taxes and insurance automatically is often what makes the loan both possible and safe.
What a Modesto file usually looks like
Modesto’s housing stock skews to one-story homes from the fifties through the seventies, College area to La Loma, and the classic file is the owner who has been in one for thirty or forty years. The mortgage is gone or nearly gone, the income is fixed, and the house is the balance sheet. A HECM line of credit turns that into a working reserve without selling and without a payment, and in 95350, Modesto’s busiest reverse mortgage ZIP at 7 of the city’s 29, that is exactly the file that keeps repeating.
The other Modesto file arrives with a moving truck: sell at Bay Area prices, buy here at Modesto prices, and the question becomes what to do with the difference. A HECM for Purchase closes the new house with roughly 55 to 70 percent down and no required monthly payment, which leaves the rest of the sale proceeds liquid. Proposition 19 often lets a 55-plus seller carry the old tax base to the new home as well; the claim goes to the Stanislaus County Assessor and has a deadline, so it belongs on the first-call checklist.
At Modesto values the costs of a reverse mortgage are proportionally the same but absolutely smaller, and so are the proceeds. I put both on one page before anyone commits to anything: what the line would be, what it costs to open, and what simply waiting a year would change. Some Modesto files end with “not yet,” and that answer is free.
How each program fits Modesto
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Modesto home lands; your own age and value may point elsewhere.
What every Modesto borrower must know
Who qualifies: homeowners 62 and older for the FHA HECM, 55 and older on many proprietary jumbo programs. The Modesto home must be the primary residence, the equity must be there, and the financial assessment has to show the obligations below are sustainable on your actual budget. No HECM closes without independent counseling first, from a HUD-approved agency you choose freely off the federal roster (national line: 800-569-4287); California then adds a cooling-off period before anything binds.
What keeps coming: the Stanislaus County tax bill in full, every line of it, homeowner’s insurance, HOA dues in the neighborhoods that have them, and the normal upkeep of a house that is now several decades old. Stay current and there is no required monthly mortgage payment for as long as you live there; fall behind and the loan can become due and payable. Automating taxes and insurance through a set-aside inside the loan is often the cleanest answer, and I set those up routinely.
What protects you: title never leaves your name or your trust. Non-recourse protection means the debt can never exceed what the home is worth when it is repaid, and when the house sells, whatever equity remains goes to you or your heirs rather than to anyone’s lender.
Owners 55 and older who sell in the Bay Area and buy in Modesto can transfer their old tax base under Proposition 19, which often matters less here than the purchase itself: a HECM for Purchase lets you buy without spending every dollar of the sale. The Prop 19 claim is filed with the Stanislaus County Assessor, and it has a deadline.
Modesto questions, straight answers
What does a reverse mortgage cost in a lower-value market like Modesto?
The categories are the same everywhere: origination (capped by HUD on a HECM), FHA mortgage insurance, third-party closing costs, and interest over time. Most costs are financed into the loan. Ask me for a line-item breakdown on your home, in writing, before you decide.
Can we use a reverse mortgage to stay in our home instead of moving?
That is the most common reason people call. Retiring a mortgage payment or adding a monthly payment from the HECM can make staying affordable, as long as taxes, insurance and upkeep stay current.
What happens to the house when we are gone?
Your heirs can sell and keep the remaining equity, or refinance and keep the house. The loan is non-recourse, so they never owe more than the home is worth, and on a HECM they can settle for 95% of appraised value if the balance is higher.
What must we keep paying after closing?
Property taxes, homeowner’s insurance, and normal upkeep.
Our house has been paid off since the nineties. Is a line of credit still worth opening?
Often, yes, and early. An unused HECM line of credit grows each year, so a line opened at 70 is meaningfully larger by 80, exactly when in-home help or a new roof tends to show up. None of Modesto’s 29 insured loans in the past year hit the federal ceiling, so the calculation starts from your full appraisal.
We want to leave the house to our daughter. Does a reverse mortgage take that away?
No. She inherits the home with a loan on it, the same as any mortgage. She can keep it by paying the balance, usually through a refinance, or sell it and keep every dollar above the payoff. Non-recourse protection caps what anyone can owe at the home’s value.
Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
The next questions on most Modesto calls, each with a full page behind it:
- What a reverse mortgage actually costs: every cost category in dollars, which ones are financed, and why “no cost” advertising is a rate decision in disguise.
- HECM line of credit compared with a bank HELOC: the Central Valley retiree’s comparison: payments, freezes, and which line is still open in a downturn.
- The reverse mortgage glossary: forty-eight disclosure terms in plain English, from expected rate to LESA.
- Who qualifies for a reverse mortgage: age, residence, equity, assessment, counseling, property type: all six tests explained.
- How reverse mortgage rates work: how the margin is set, what it changes, and how to compare two offers properly.
- Helping a parent decide: the page to send your kids before the family talks it over.
If a Modesto property somehow runs past the federal line, the page to read is jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Modesto numbers.
Fifteen minutes gets your Modesto figures in writing: the line, the costs, and the wait-a-year comparison.
- A call back within minutes during California business hours
- The numbers arrive on paper, not in a pitch
- “Not yet” is an answer I give freely
Rather talk it through now?
Describe the house and what you are solving for, and I will tell you plainly whether a reverse mortgage is the tool, including when the honest answer is to wait. Modesto files are small enough that the arithmetic settles most arguments fast.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide