Reverse Mortgage Broker Serving Corona, California
FHA insured 26 reverse mortgages in Corona in the past year, and only one reached the FHA limit. The HECM counts nearly every Corona home at full value.
The federal file on Corona: the HECM reaches almost everything.
HUD logs every FHA-insured reverse mortgage in the country, loan by loan. These are the Riverside County and Corona lines from the last twelve monthly releases, September 2025 through August 2026.
| HECMs insured by FHA, Riverside County | 431 |
| Of those, purchases (HECM for Purchase) | 45 |
| Reached the FHA ceiling | 3.0% |
| In Corona itself | 26 |
| Corona: reached the ceiling | 3.8% |
| California overall vs. the rest of the US | 20.2% vs 3.0% |
Across Riverside County, 3.0% of insured loans reached the FHA ceiling. On the other 97, the standard HECM calculation captured the appraisal in full, which is another way of saying the federal program works well here.
Corona itself logged 26, with a single loan at the ceiling. The jumbo conversation is occasionally real here, usually up in the estates, and the HECM wins everywhere else.
Where these figures come from. Counted by me from the FHA HECM Single-Family Portfolio Snapshot, the loan-level file HUD publishes every month. The last twelve monthly releases, September 2025 through August 2026. HUD counts each loan in the month FHA insured it (its endorsement), usually within about two months of closing, so these are insurance months, not closing months. A loan is counted as reaching the ceiling when its maximum claim amount equals the limit that applied to its case number: $1,209,750 for 2025 case numbers and $1,249,125 for 2026. No endorsements at all were processed in October 2025 — in HUD’s words, “due to the lapse in appropriations covering the entire month” — so that release is empty and the figures cover eleven months of endorsements. These are FHA-insured HECM loans only; proprietary jumbo lending is not federally insured and appears in no public dataset. Every California county and city in one table →
Corona by ZIP code
The four ZIP codes Zillow tracks for Corona, each with the HECMs HUD recorded there in the past year and the typical home value measured against the 2026 FHA limit.
Corona HECMs insured in the past year
All 4 Corona ZIP codes have a typical value under the $1,249,125 limit, from about $684,000 to $857,000. The most loans were in 92883: 8 of the 26.
| ZIP code | HECMs insured | At the FHA ceiling | Typical home value | Under or over the limit |
|---|---|---|---|---|
| 92879 | 3 | 0 | $684,000 | Under |
| 92881 | 4 | 0 | $857,000 | Under |
| 92882 | 7 | 0 | $770,000 | Under |
| 92883 | 8 | 1 | $746,000 | Under |
All 26 HECMs HUD recorded with a Corona address; 4 of them carried ZIP codes Zillow does not assign to Corona, so they are not in the table. The limit is the 2026 HECM maximum claim amount of $1,249,125.
HUD’s list shows 13 FHA-approved condominium projects with a Corona mailing address (searched October 16, 2026). A unit in a project that is not on the list can still qualify through FHA’s single-unit approval, which adds stricter income and payment-history tests for HECM borrowers (HUD Mortgagee Letter 2019-17). Search HUD’s condominium list →
Where these figures come from. Loans: the HUD HECM Snapshot records behind this page’s other figures, September 2025 through August 2026 (the months FHA insured each loan), by the ZIP code HUD records for each Corona loan. Typical home values: Zillow Home Value Index for each ZIP code, all homes, data through September 30, 2026, rounded to the nearest $1,000. A typical value is the middle of the market, so plenty of homes in an “under” ZIP code are worth more, and the reverse. Condominiums: HUD’s FHA condominium list, status Approved.
The Corona bottom line: the FHA-insured HECM carries nearly every file in town. HUD recorded 26 Corona HECMs in the past year and exactly one reached the FHA ceiling, so for homeowners 62 and older the federal calculation almost always counts the whole house. The jumbo programs earn their keep for owners aged 55 to 61 and for estate properties above the limit, on values to $4 million. Whichever applies, no monthly principal-and-interest payment is required while you live in the home with taxes, insurance, and upkeep current.
2026 HECM limit: HUD Mortgagee Letter 2025-22. Counseling and California’s seven-day period: Cal. Civ. Code §1923.2. Loan counts: HUD FHA HECM Single-Family Portfolio Snapshot, September 2025 through August 2026.
The Corona picture
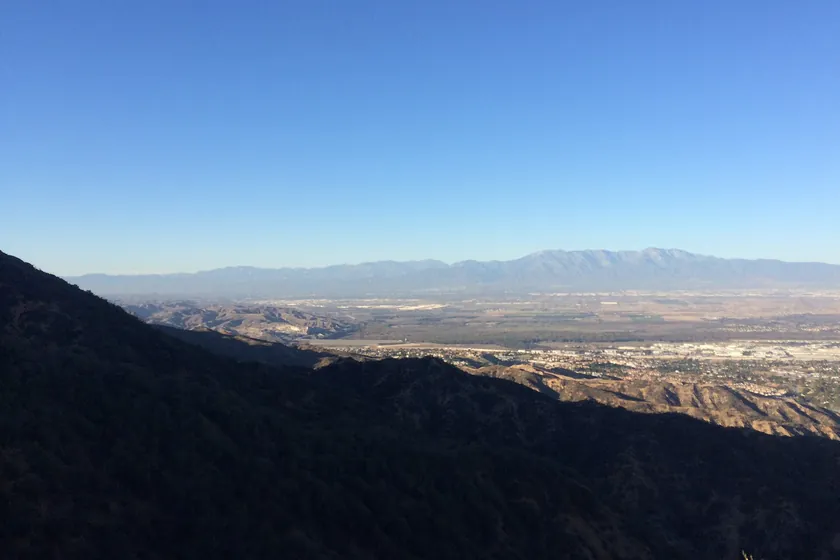
Corona grew up around its circle, Grand Boulevard’s loop around the original town, and then grew outward fast as the 91 freeway turned it into a commuter city for Orange County and Los Angeles. The families who bought in the 1980s and 1990s in Sierra del Oro, South Corona and the neighborhoods around them are reaching retirement with a lot of equity and, often, a mortgage they would rather not carry into their seventies.
HUD’s records put Corona firmly in HECM territory: one of 26 local HECMs reached the FHA ceiling in the past year, in a county where only 3.0% did. The federally insured program counts almost every Corona home at full value, so the useful conversation is about structure: retiring the mortgage payment, keeping a growing line of credit in reserve, or both.
Many of Corona’s newer tracts, and the communities toward Dos Lagos and Temescal Valley, were financed with Mello-Roos districts. Those special taxes appear on the property tax bill and are part of the obligation on a reverse mortgage. I read the bill with you before quoting anything, so the budget after closing is real.
Three Corona files, start to finish
Corona equity was built the hard way: decades on the 91 while the mortgage got paid down and the tract appreciated around you. The file that repeats here is a couple in their late sixties in south Corona with a stretch of refinance still left to pay. The HECM retires that monthly payment, and the equity that sat locked in the walls starts carrying the household instead of the other way around. With typical Corona values running from the high $600,000s, the numbers usually clear with room to spare.
Corona’s busiest reverse mortgage ZIP code in the past year was 92883, the corridor south along I-15 through Temescal Valley, where Trilogy at Glen Ivy and the newer tracts carry Corona addresses. Eight of the city’s 26 HECMs landed there. Many of these owners bought for retirement and want the line of credit standing before they need it. The unused line grows over time, which rewards opening it early rather than waiting for the roof or the air conditioner to force the issue.
South Corona tax bills often carry Mello-Roos and other special assessments, and every line of that bill must stay current with a reverse mortgage, exactly as before. On a tight budget I structure a set-aside so taxes and insurance pay themselves from the loan. And because one Corona home did reach the FHA ceiling in the past year, the only one in the city, a property well above the neighborhood norm gets the HECM and the jumbo run side by side before anyone chooses.
How each program fits Corona
Same broker, same phone number, three different instruments. I run the ones that apply to your home side by side, and the numbers pick the winner, not the sales pitch. The highlighted row is where a typical Corona home lands; your own age and value may point elsewhere.
What every Corona borrower must know
Who qualifies: for the FHA HECM, homeowners 62 and older; many proprietary jumbo programs open at 55. The home must be your primary residence, the equity has to be there, and a financial assessment must show you can carry the obligations below. Before any HECM you meet with an independent HUD-approved counselor, chosen by you from HUD’s own roster (national line: 800-569-4287), and California adds a cooling-off period on top. Nobody signs a Corona file in a hurry.
What stays on you: the full property tax bill, Mello-Roos and all, homeowner’s insurance, HOA dues where you have them, and normal upkeep. No monthly mortgage payment is required while you live in the home and keep those current; let them lapse and the loan can become due and payable. Where automating the bills is the safer plan, I build a set-aside into the loan so they pay themselves.
What protects you: title stays in your name or your trust. The loan is non-recourse, so neither you nor your kids can ever owe more than the home is worth when it is repaid. And when the home finally sells, every remaining dollar of equity after payoff belongs to you or your heirs, never the lender.
Mello-Roos special taxes and other district charges on the Riverside County bill are part of the property tax obligation. They usually expire after a set number of years, which can improve the budget later; the county’s special tax listing shows the remaining term. Owners 55 and older moving within California may also carry their tax base under Proposition 19.
Corona questions, straight answers
We still have 12 years left on our mortgage. Can a reverse mortgage pay it off?
Often, yes, if the proceeds for your age and home value cover the payoff. The reverse mortgage retires the old loan at closing, and no monthly mortgage payment is required afterward while you live in the home and keep taxes, insurance and upkeep current. I will show you the payoff math in writing first.
Our tax bill includes Mello-Roos. Does that hurt us?
It is part of the budget, not a barrier. HUD’s financial assessment includes it, and so does my analysis. If cash flow is tight, a set-aside can pay the taxes automatically.
Would a jumbo reverse mortgage give us more?
For most Corona homes, no. The HECM already counts the full value. A jumbo mainly helps owners aged 55 to 61 or homes above the $1,249,125 limit.
What must we keep paying after closing?
Property taxes including special assessments, homeowner’s insurance, HOA dues where they apply, and normal upkeep.
We bought in Eagle Glen in 1999 and refinanced twice. How much of the value counts?
All of it, up to the FHA limit. The HECM calculation starts from the appraised value or the $1,249,125 limit, whichever is lower, then applies your age and the rate. Only one Corona loan reached that limit in the past year, so in almost every case the whole appraisal is working for you.
Do you come out to Corona, or is this all by phone?
Most of a reverse mortgage happens by phone and email. The appraiser comes to the house, counseling is scheduled wherever suits you, and signing is done with a mobile notary at your kitchen table. You never need to find my office, and I answer my own phone.
Written by Ken Adler
Every page on this site is written and maintained by me: the same person who answers the phone, runs your numbers, and handles your file start to finish. No call center, no hand-offs, no lead-selling. More about how I work →
Six questions that come up on Corona files more than any others, each with a full page behind it instead of a buried paragraph:
- What a reverse mortgage actually costs: the six cost categories, which ones are financed rather than paid at the table, and why “no cost” advertising never survives the math.
- HECM line of credit compared with a bank HELOC: required payments, freeze risk, and the cases where the HELOC really is the better tool for a Corona homeowner.
- The reverse mortgage glossary: forty-eight terms in plain English, for anyone staring at a disclosure wondering what a principal limit factor is.
- Who qualifies for a reverse mortgage: all six requirements on one page, plus the jumbo route from age 55.
- How reverse mortgage rates work: index, margin, the expected rate, and how to put two quotes side by side.
- Helping a parent decide: what adult children should know about the house, the inheritance, and the questions worth asking early.
If your Corona home sits above what the FHA calculation will count, start instead with jumbo reverse mortgages for California homes.
Want a rough number before you call?
The calculator takes an age and a home value and shows an estimate on screen, with every cost line. No name, phone or email needed. Moving or inheriting? See how Prop 19 treats your property tax base.
Let’s run your Corona numbers.
Fifteen minutes and you will know what your age and your Corona equity actually produce, on paper, HECM next to jumbo.
- A call back within minutes during California business hours
- Your figures in writing before anyone asks you to commit
- If the right answer is no loan, that is the answer you get
Rather talk it through now?
Tell me what you are trying to do and I will tell you, plainly, whether a reverse mortgage is the right tool for it. When it is not, you will hear that on the same call, along with what I would look at instead.
(818) 674-7284Prefer to read first?
Request the free California reverse mortgage guide. It arrives instantly, with no sales calls attached.
Get the Free Guide